Real Estate Strategy
Want to Buy Your Next Home but Need to Sell Your Current One?
There are more ways to make your next move than simply selling first and hoping the right home is still available.
For many homeowners, the biggest challenge isn't deciding whether they want to move. It's figuring out how.
You may have substantial equity tied up in your current home, a mortgage rate you'd prefer not to give up, and a very specific idea of what you're looking for next.
Selling before finding another home can feel risky. Buying before selling may seem financially impossible. And trying to coordinate both transactions at the same time can feel overwhelming.
The good news is that there are several strategies worth exploring, from bridge financing and contingent offers to renting out your current home or negotiating flexible possession terms.
The right approach depends on your equity, financial position, local market conditions, and tolerance for risk.
By Ronnie Jenkins, REALTOR® | Compass | Silicon Valley & South Orange CountyPublished · Last reviewed
Can You Buy a House Before Selling Your Current Home?
Yes. Some homeowners can purchase their next home before selling their current property through bridge financing, available cash or other assets, home equity borrowing, specialized buy-before-you-sell programs, or financing that accounts for rental income from the existing home.
Other homeowners may benefit from selling first, negotiating a rent-back, or structuring a purchase contingent on selling their current property.
Each option has different qualification requirements, costs, contractual implications, and risks. The best strategy depends on your existing equity, income, cash reserves, mortgage obligations, market conditions, and the timing of your next move.
The short answer
You may have more options than you think. The key is understanding which ones actually work for your situation.
Eight ways to sell and buy a home
Eight Strategies for Getting From This Home to the Next
Strategy 01
Sell First, Then Buy
How it works
The most straightforward strategy. You sell your existing home, find out what your sale actually nets, and use that equity toward your next purchase.
A well-planned timeline takes much of the risk out of this approach. That means pricing and preparing the listing carefully, getting pre-approved for the next purchase before you list, shortlisting neighborhoods in advance, and lining up a rent-back or short-term rental before you need one.
- Greater certainty about available funds.
- No need to carry two mortgages after the sale.
- Potentially simpler loan qualification.
- Ability to make an offer without a home-sale contingency once the sale closes.
- Who it may suit
- Homeowners who need their sale proceeds for the next down payment, prefer financial certainty, or can't comfortably qualify for two housing payments.
- Primary advantage
- You know exactly what you have to spend, and you shop as a non-contingent buyer.
- Main drawbacks
- Temporary housing may be needed.
- Moving twice could increase expenses.
- The ideal next home may not be available immediately.
- Questions to ask a professional
- How long could we comfortably live in temporary housing?
- Would a buyer accept a rent-back, and for how long?
- What should my pre-approval look like before we list?
Strategy 02
Buy Contingent on Selling Your Existing Home
How it works
You make an offer on the next home that includes a negotiated contingency tied to the sale of your current home.
The exact terms are negotiated. A contingency might require you to list your home, enter escrow, or close the sale by agreed deadlines. Some sellers accept these terms only with a provision that lets them keep marketing their home and ask you to remove the contingency, or step aside, if a stronger offer arrives. This is often called a kick-out or continued-marketing provision.
The protection you have depends entirely on the written agreement. Cancellation rights and deposit treatment are not automatic and should be reviewed carefully before you sign.
- May reduce exposure to owning two homes.
- Can link purchase financing to the existing home's proceeds.
- Who it may suit
- Buyers whose home is ready to list, or already in escrow, in a market where sellers have time to wait.
- Primary advantage
- You can secure the next home while limiting the risk of owning two at once.
- Main drawbacks
- Sellers may favor competing offers without contingencies.
- Contractual timelines and removal provisions matter.
- Failure to satisfy contract conditions can create significant risks, including possible loss of your deposit depending on the contract.
- Questions to ask a professional
- What deadlines does the contingency set, and what happens if I miss one?
- Is there a kick-out or continued-marketing provision, and how much notice do I get?
- How strong is my current home's likely sale timeline?
Strategy 03
Sell Contingent on Finding a Replacement Home
How it works
You market and sell your current home while negotiating a seller contingency for finding a suitable replacement property.
The sale is structured around locating your next home. Seller and buyer negotiate the deadlines and the rights each side has if no replacement is found. The contingency must be clearly documented, buyer acceptance is not guaranteed, and a poorly structured agreement can lead to disputes.
- Who it may suit
- Sellers with a highly desirable home and a narrow search for the next one, often in a market where buyers are competing for listings.
- Primary advantage
- You may keep more control over the transition and avoid selling without somewhere to go.
- Main drawbacks
- Not all buyers will accept the terms.
- The contractual protection depends on how the agreement is written.
- It can reduce the pool of interested buyers or affect price.
- Questions to ask a professional
- How long a search period would buyers reasonably accept?
- What exactly counts as a 'suitable' replacement in the contract?
- Could a rent-back give me similar protection with less friction?
Strategy 04
Use a Bridge Loan
How it works
A bridge loan is short-term financing that may let eligible homeowners access equity in their current home before it sells, often to fund the down payment on the next one. It is typically repaid when the existing home sells.
Lenders look at your equity and collateral, and you still owe your existing mortgage while the bridge loan is outstanding. Bridge loans usually carry higher interest rates than standard mortgages, plus origination fees and other costs.
Fannie Mae accepts bridge loan funds for a purchase under specified conditions, including that the bridge loan isn't cross-collateralized against the new home and that the lender documents your ability to carry the new home, the current home, the bridge loan, and your other obligations.
If the sale takes longer than expected or closes at a lower price, repayment can become harder and costlier. Bridge financing is never a guarantee of approval.
Source: Fannie Mae, Selling Guide B3-4.3-14, Bridge/Swing Loans
- Who it may suit
- Homeowners with substantial equity and strong income who want to buy before selling, without a sale contingency.
- Primary advantage
- You can make a stronger, non-contingent offer on the next home and sell afterward.
- Main drawbacks
- Higher interest and origination costs than a standard mortgage.
- You may carry three payments at once: existing mortgage, bridge loan and new mortgage.
- A slow or disappointing sale increases cost and risk.
- Questions to ask a professional
- What are the total costs, including fees, interest and any prepayment terms?
- How long is the term, and what happens if my home hasn't sold by then?
- Can I qualify with all three payments counted?
Strategy 05
Use a HELOC or Other Equity-Based Financing
How it works
Some homeowners can tap existing equity through a home equity line of credit (HELOC) or other asset-secured borrowing, then use those funds toward the next purchase.
Things to weigh include how much equity lenders will let you borrow against, variable interest rates, draw periods, the added monthly payment, and whether your existing lender allows a second lien. Timing matters too: many lenders won't open a HELOC on a home that is already listed for sale, so it usually needs to be in place before you list.
Using equity before your sale is complete means you are borrowing against a price you haven't yet achieved. Fannie Mae treats funds borrowed against an asset as an acceptable source for down payment and closing costs, but the payments still count in qualification.
Securities-backed lending, which borrows against an investment portfolio, is a specialized option for some qualified borrowers. Market declines can trigger maintenance calls or forced sales of the pledged investments, so it needs careful review with a financial advisor. It isn't suitable for everyone, and this guide doesn't recommend speculative or unsuitable borrowing.
Source: Fannie Mae, Selling Guide B3-4.3-15, Borrowed Funds Secured by an Asset
- Who it may suit
- Owners with meaningful equity who plan ahead, open the line before listing, and can absorb a variable payment.
- Primary advantage
- Flexible access to equity, often at lower upfront cost than a bridge loan.
- Main drawbacks
- Variable rates can raise payments.
- Adds a monthly obligation that affects qualification.
- May need to be in place before the home is listed.
- Questions to ask a professional
- Will my lender open a HELOC if I plan to list soon?
- How will the payment affect my qualification for the next loan?
- What happens to my investments if markets fall while a securities-backed loan is outstanding?
Strategy 06
Keep Your Current Home as a Rental
How it works
Some homeowners buy a new primary residence and convert their current home into a rental. You keep the property, keep its existing mortgage terms, collect rent, and keep any long-term appreciation.
The financial and underwriting details are critical, and the income a lender lets you count is different from the cash the property actually produces.
- Retaining ownership of the existing property.
- Continuing to hold a mortgage with favorable existing terms.
- Generating rental income.
- Potential long-term property appreciation.
Source: Fannie Mae, Selling Guide B3-3.8-05, Rental Income from Non-Subject Property: Departing Residence
- Who it may suit
- Owners with a low existing rate, healthy reserves, and genuine interest in being a landlord.
- Primary advantage
- You keep an appreciating asset and a favorable mortgage while moving on.
- Main drawbacks
- Landlord responsibilities, vacancy and repairs.
- Insurance changes from owner-occupied to rental coverage.
- Capital gains and tax treatment can change once a home stops being your primary residence.
- The market could decline while you own two properties.
- Questions to ask a professional
- What does a lender's market-rent analysis show for my home?
- How would converting to a rental affect my taxes if I sell later?
- Do I have the reserves the lender will require?
Current Fannie Mae guidance for departing primary residences
Under the Fannie Mae Selling Guide update issued September 2, 2026, rental income from a departing residence is based on documented market rents, such as an appraisal with market rents, a comparable rent schedule, or a market analysis using at least three comparable rentals.
The lender generally multiplies the documented monthly gross market rent by 75%, then subtracts the departing home's principal, interest, taxes, insurance, and association dues (PITIA).
A positive result can be used to offset the departing home's housing payment only. It isn't added as extra qualifying income. A negative result is counted in your debt-to-income ratio.
Under this guideline, lease agreements are not permitted as the documentation for a departing residence's rent. If you have less than 12 months of property management experience, the lender must also verify six months of reserves for the departing home's PITIA, in addition to other reserve requirements.
Individual lenders may add their own restrictions, and loan programs other than Fannie Mae conventional loans follow different rules. Implementation timing matters, so confirm current requirements with your lender.
Illustrative example
- Potential monthly market rent
- $6,000
- 75% qualifying factor
- $4,500
- Current monthly PITIA
- −$4,200
- Adjusted amount
- +$300
Under this Fannie Mae framework, the +$300 generally offsets the departing home's housing expense. It does not create $300 of additional qualifying income.
This is a financing illustration, not a finding that the property would cash-flow positively. Actual rental cash flow also depends on vacancy, management, maintenance, repairs, taxes, insurance and other costs.
Income a lender lets you count for qualification is not the same as the cash a rental actually puts in your pocket. Plan for both.
Strategy 07
Buy First, Then Recast the Mortgage After Selling
How it works
Some borrowers qualify for the new home's mortgage before selling their existing one. After the old home sells, they put a large share of the proceeds toward the new loan's principal.
If the loan and servicer allow it, a mortgage recast re-amortizes the remaining balance and lowers the required monthly principal-and-interest payment. A recast typically keeps your existing interest rate and loan term. It may involve a fee and a minimum principal reduction, and not all loan types or servicers allow it. Government-backed loans often don't.
You must qualify for the original, larger mortgage first. This approach can work well for homeowners with enough income and cash to qualify before their old home sells.
- Who it may suit
- High-income buyers with strong reserves who want a non-contingent purchase without a bridge loan.
- Primary advantage
- Buy first, then lower your payment without refinancing or giving up your rate.
- Main drawbacks
- Requires qualifying for the larger loan, often with both homes counted.
- Higher payments until the old home sells.
- Recast availability and fees vary by servicer.
- Questions to ask a professional
- Does my servicer allow recasting, and what are the fee and minimum principal reduction?
- Can I qualify with both housing payments counted?
- How much cash do I need upfront?
Strategy 08
Negotiate a Rent-Back, Delayed Possession, or Alternative Closing
How it works
A seller can negotiate to stay in the sold home for a period after closing, often called a rent-back, or coordinate other possession and closing dates so the move happens once.
Details matter. Buyers' lenders often limit how long a seller can stay, because the buyer must move in within a set time to keep owner-occupied financing. Insurance, liability, security deposits and the written agreement all need attention. The buyer also has to be flexible enough to accept the arrangement.
Some companies offer institutional buy-before-you-sell programs that help you buy first, for example by temporarily purchasing the new home or guaranteeing a sale price on your current one. Fees, availability, lender requirements and terms vary considerably, so compare total cost carefully.
- Who it may suit
- Sellers who want to sell first but move only once, and buyers in no hurry to take possession.
- Primary advantage
- Turns 'sell first' into a single, calmer move.
- Main drawbacks
- Not every buyer or lender can accommodate it.
- Occupancy limits and insurance must be handled correctly.
- Institutional programs can be expensive.
- Questions to ask a professional
- How long a rent-back will the buyer's lender allow?
- Who insures what during the rent-back?
- What would a buy-before-you-sell program cost in total?
Which strategy is right for you?
Compare Your Options
Sell First, Then Buy
- Buy before or after selling?
- After
- Equity needed upfront?
- No, proceeds fund the purchase
- Two housing payments?
- Unlikely
- Main advantage
- Certainty about funds
- Primary risk
- Temporary housing or missing the next home
- Professional review
- Agent, lender
Buy Contingent on Selling Your Existing Home
- Buy before or after selling?
- Simultaneous
- Equity needed upfront?
- Usually no
- Two housing payments?
- Limited
- Main advantage
- Reduced exposure to two homes
- Primary risk
- Less competitive offer; deadlines
- Professional review
- Agent, attorney if needed
Sell Contingent on Finding a Replacement Home
- Buy before or after selling?
- Simultaneous
- Equity needed upfront?
- No
- Two housing payments?
- Unlikely
- Main advantage
- Control over the transition
- Primary risk
- Fewer interested buyers; disputes
- Professional review
- Agent, attorney if needed
Use a Bridge Loan
- Buy before or after selling?
- Before
- Equity needed upfront?
- Yes, as collateral
- Two housing payments?
- Yes, plus bridge payment
- Main advantage
- Non-contingent purchase
- Primary risk
- Cost and sale delays
- Professional review
- Lender, agent
Use a HELOC or Other Equity-Based Financing
- Buy before or after selling?
- Before
- Equity needed upfront?
- Yes, borrowed against
- Two housing payments?
- Yes, plus HELOC payment
- Main advantage
- Flexible access to equity
- Primary risk
- Variable rates; added debt
- Professional review
- Lender, financial advisor
Keep Your Current Home as a Rental
- Buy before or after selling?
- Before
- Equity needed upfront?
- Down payment from other funds
- Two housing payments?
- Yes, offset by rent
- Main advantage
- Keep asset and existing rate
- Primary risk
- Landlord, vacancy and market risk
- Professional review
- Lender, tax professional
Buy First, Then Recast the Mortgage After Selling
- Buy before or after selling?
- Before
- Equity needed upfront?
- Cash for initial down payment
- Two housing payments?
- Yes, until the sale
- Main advantage
- Lower payment after sale, same rate
- Primary risk
- Qualifying for the larger loan
- Professional review
- Lender, servicer
Negotiate a Rent-Back, Delayed Possession, or Alternative Closing
- Buy before or after selling?
- After, one move
- Equity needed upfront?
- No
- Two housing payments?
- Unlikely
- Main advantage
- Move only once
- Primary risk
- Lender occupancy limits; insurance
- Professional review
- Agent, insurance
The best strategy isn't necessarily the most creative one. It's the one that provides the right combination of financial flexibility, manageable risk, and the ability to secure a home you genuinely want.
Interactive
Find Your Sell + Buy Path
Strategies to investigate
Answer all four questions to see two or three starting points.
Educational starting points only. Financing and contractual suitability require individual review.
Review My Options With RonnieWhat about your low mortgage rate?
Is Giving Up a 3% or 4% Mortgage a Reason Not to Move?
A low existing mortgage rate is a valuable financial advantage. But it is only one part of the decision.
A home that no longer fits your needs may create costs or compromises that aren't reflected in the mortgage payment.
California property tax can also change when you buy a new home. Some homeowners 55 and older may be able to transfer their tax base under Proposition 19; confirm eligibility with your county assessor.
Before deciding to stay solely because of the rate, compare:
- Current housing expenses
- Expected proceeds from selling
- The cost of the replacement home
- New mortgage payment
- Property taxes and insurance
- Expected duration of ownership
- Lifestyle considerations
- Potential rental income
- Future financial flexibility
The objective isn't to ignore the value of an existing mortgage. It's to determine whether keeping that mortgage is more valuable than making the move you actually want.
Hypothetical case study
A Realistic Move-Up Planning Example
A hypothetical homeowner has substantial equity and wants a larger home. Adjust the assumptions to see how three approaches compare. These are illustrations, not loan offers or quotes.
Adjust the assumptions
Estimated equity after 5% selling costs ($90,000): $1,060,000
Option A
Sell first, buy with actual proceeds
- Cash needed at purchase closing
- $39,000
- Financing fees and bridge interest
- $0
- Temporary carrying costs (4 mo)
- $26,000
- New loan amount
- $1,540,000
- Monthly P&I before the sale
- $9,482
- Monthly P&I after the transition
- $9,482
- Cash reserves remaining
- $635,000
Temporary housing and a possible second move; the right home may not be available.
Option B
Bridge loan, buy before selling
- Cash needed at purchase closing
- $54,900
- Financing fees and bridge interest
- $47,700
- Temporary carrying costs (4 mo)
- $51,000
- New loan amount
- $1,540,000
- Monthly P&I before the sale
- $9,482
- Monthly P&I after the transition
- $9,482
- Cash reserves remaining
- $594,100
A slow or lower sale raises bridge costs; three payments during the overlap.
Option C
Independent financing, then recast
- Cash needed at purchase closing
- $559,000
- Financing fees and bridge interest
- $250
- Temporary carrying costs (4 mo)
- $19,200
- New loan amount
- $2,080,000
- Monthly P&I before the sale
- $12,807
- Monthly P&I after the transition
- $6,255
- Cash reserves remaining
- $121,550
Must qualify for the larger loan; higher payment until the sale; servicer must allow recasting.
Assumes a 30-year fixed loan at the same rate for every option, the full net sale proceeds go toward the purchase (Options A and B) or the principal reduction (Option C), the bridge loan equals the net proceeds and is interest-only, and taxes, insurance and HOA on the new home are excluded from the P&I figure. Option C ends with a lower payment largely because more total cash went in. Lenders, fees and rates vary.
How Ronnie coordinates two transactions
A Move Should Have One Strategy, Not Two Separate Plans
- 1
Evaluate Your Current Home
Understand estimated market value, equity, likely sale timeline, and current competition.
- 2
Establish Your Next Purchase Requirements
Determine location, price range, must-haves, financing constraints, and flexibility.
- 3
Select the Transaction Structure
Evaluate possible financing, contingencies, sale timing, and backup plans.
- 4
Coordinate Both Sides
Prepare the listing, monitor suitable purchases, manage deadlines, and communicate with the relevant professionals.
- 5
Execute the Move
Coordinate the sale, purchase, financing, escrow, possession, and relocation logistics.
Ronnie has worked with clients in both Silicon Valley and South Orange County, including homeowners who sell in one region and buy in the other. One advisor coordinating both sides means one timeline, one set of deadlines, and fewer surprises.
Ronnie's perspective
Don't Let the Logistics Make the Decision for You
One of the most common reasons homeowners postpone a move is that they can't figure out how to sell and buy at the same time.
They know what they want next, but they're worried about ending up between homes, carrying two mortgages, or losing the opportunity to buy the right property.
The reality is that there are often several ways to approach the situation. My role is to help evaluate the options, coordinate the right professionals, and create a strategy that minimizes unnecessary risk.
You shouldn't have to figure out both transactions on your own before deciding whether a move is possible.
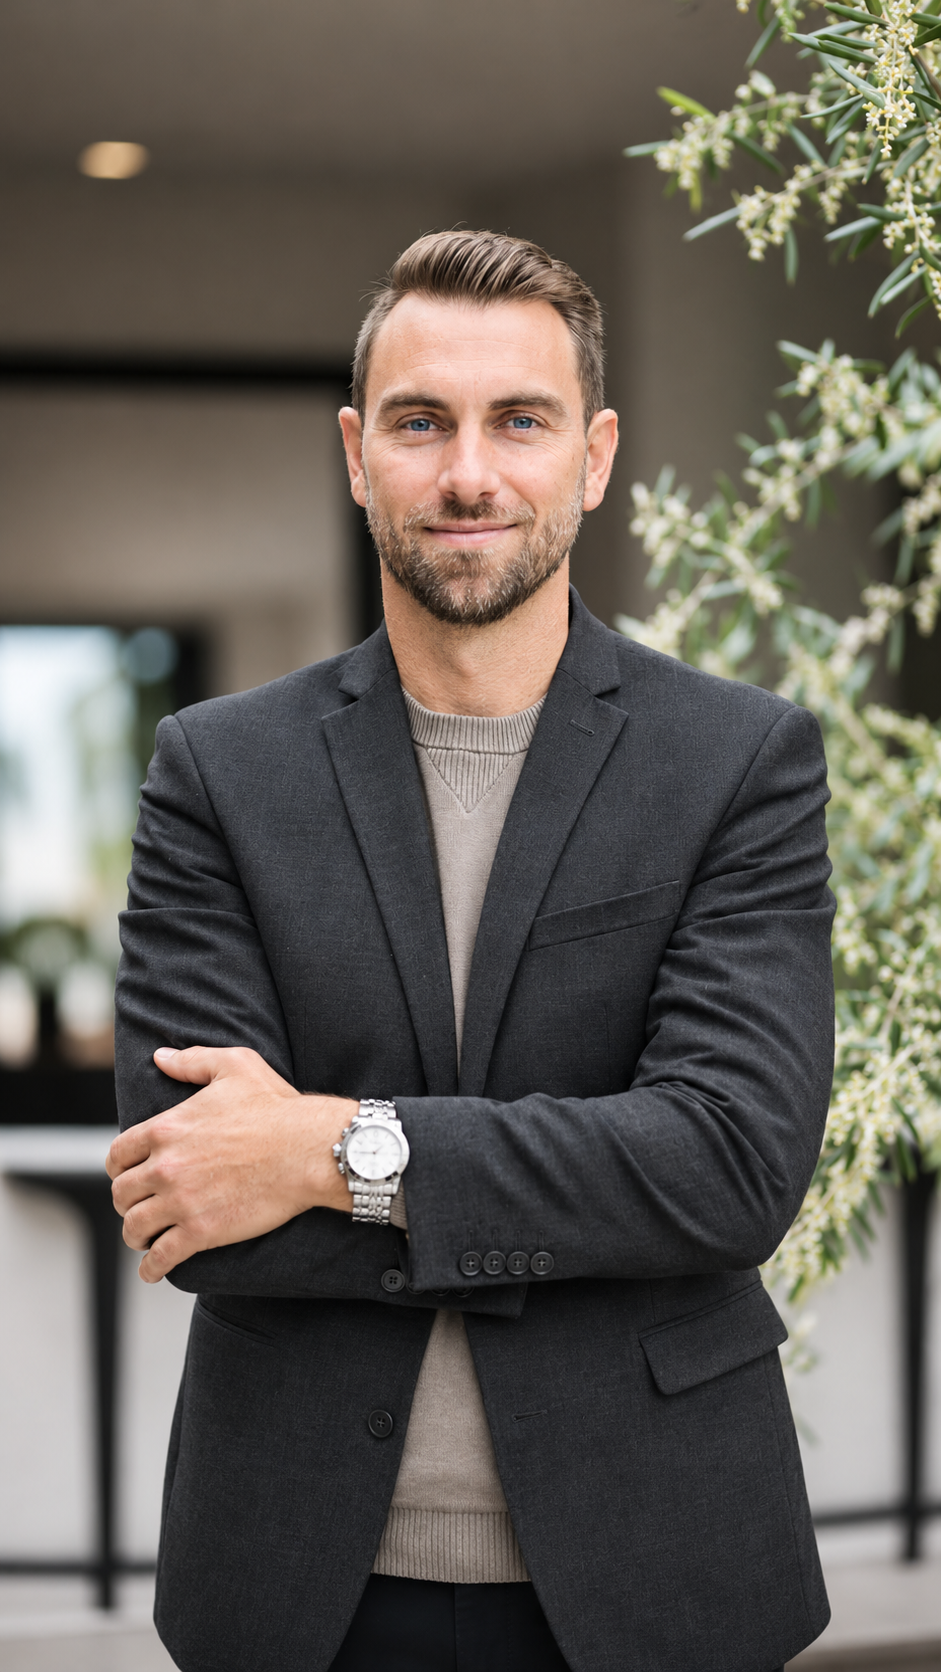
Ronnie JenkinsREALTOR® | CompassCalifornia DRE #01922959
More about RonnieFrequently Asked Questions About Selling and Buying
Can I buy a house before selling my current home?
Often, yes. Common routes include a bridge loan, a HELOC opened before listing, cash or other assets, qualifying for the new loan with both payments counted and then recasting after the sale, or using rental income from your current home. Each depends on your equity, income and reserves, so start with a lender conversation before you shop.
What is a bridge loan, and how does it work?
A bridge loan is short-term financing secured by your current home's equity. It can fund the down payment on your next home before the old one sells, and it's typically repaid from the sale proceeds. Expect higher rates and fees than a standard mortgage, and plan for what happens if the sale takes longer than expected.
Can I use equity from my current home to buy another?
Yes, through a sale, a bridge loan, a HELOC or a cash-out refinance. Before a sale, you're borrowing against equity, which adds a payment that lenders count when you qualify. Many lenders won't open a HELOC once a home is listed, so timing matters.
Can I rent out my current home and use the rental income to qualify?
Possibly. Under Fannie Mae's departing-residence guidance, a lender generally takes 75% of documented market rent and subtracts the home's PITIA. A positive result offsets that home's payment; a negative result is counted as debt. Reserve requirements may apply, and lenders can add their own rules.
Does Fannie Mae require a lease to use rental income from a departing residence?
No. Under the September 2, 2026 guidance, lease agreements are not permitted for a departing residence. Market rent is documented with an appraisal including market rents, a comparable rent schedule, or a market analysis using at least three comparable rentals. Other loan programs may differ.
Can I make an offer contingent on selling my home?
Yes, if the seller agrees. The contingency sets deadlines for listing, entering escrow or closing your sale, and sellers often ask for a kick-out provision so they can keep marketing. These offers can be less competitive, and your protections depend on the contract.
Can I sell my house contingent on finding a replacement property?
Yes, if your buyer agrees. The agreement should clearly define the search period, what counts as a replacement, and each side's rights if none is found. Not every buyer will accept it, so it tends to work best for highly desirable homes.
What happens if my existing home doesn't sell?
It depends on your structure. With a sale contingency, your contract terms decide what happens. With a bridge loan or HELOC, you keep carrying payments until it sells, and you may need to reduce the price, rent the home or refinance. That's why reserves and a realistic pricing plan matter.
Can I keep my low mortgage rate and rent out my house?
Usually you can keep the existing loan when you move out, but check your loan documents, tell your insurer, and switch to landlord coverage. Many mortgages require owner occupancy only for an initial period, typically one year. Confirm your terms before converting.
Can I recast my mortgage after selling my previous home?
If your loan and servicer allow it. A recast applies a lump-sum principal payment and re-amortizes the balance, usually keeping the rate and term. There's often a fee and minimum payment, and many government-backed loans don't permit recasting. Ask before you choose a lender.
How does a rent-back work in California?
After closing, the seller stays in the home for an agreed period under a written agreement that covers rent, deposit, condition, insurance and move-out date. The buyer's lender may limit the length because the buyer must occupy the home within a set time. Short rent-backs are common; long ones are harder.
What is the safest way to coordinate selling and buying?
There isn't one universally safest method. Selling first gives the most financial certainty; buying first gives the most housing certainty. The right choice balances your equity, income, reserves and how specific your next home needs to be. A coordinated plan with backup options reduces risk more than any single structure.
Can I sell in Silicon Valley and buy in Orange County with the same agent?
Yes. Ronnie works with clients in both Silicon Valley and South Orange County, so one advisor can coordinate the sale, the purchase and the timeline between them.
How much cash should I keep in reserve when making a move?
Enough to cover overlapping payments, temporary housing, moving costs and surprises without strain. Lenders set minimum reserves for some loans, such as six months of the departing home's PITIA in certain rental scenarios, but your comfort level may call for more. Talk with your lender and financial advisor.
Sources and Further Reading
- Fannie Mae, Selling Guide B3-3.8-05, Rental Income from Non-Subject Property: Departing Residence. Updated .Announcement SEL-2026-08. 75% market-rent factor, offset-only treatment, no lease agreements, six-month reserve rule.
- Fannie Mae, Selling Guide B3-4.3-14, Bridge/Swing Loans
- Fannie Mae, Selling Guide B3-4.3-15, Borrowed Funds Secured by an Asset
- Fannie Mae, Recast Mortgage job aid
- Consumer Financial Protection Bureau, Mortgage and home equity consumer resources
- California Association of REALTORS®, Consumer and market resources
This guide is general information, not financial, lending, legal, or tax advice. Ronnie Jenkins is a real estate agent, not a mortgage loan officer, attorney or tax professional. Mortgage qualification, tax treatment and contractual protections must be reviewed with qualified professionals. Lender and loan-program requirements vary and change. Last reviewed .