Home Buying for Medical Professionals
Your Medical Career Is Moving Forward. Your Homeownership Goals Can Too.
Specialized mortgage programs, strategic home buying guidance, and personalized relocation support for California's medical professionals.
Buying a home as a medical professional comes with unique opportunities and challenges.
From substantial student loans and limited early-career savings to employment contracts and changing income, your financial situation may not fit the traditional home-buying model.
But that doesn't necessarily mean you need to wait years before becoming a homeowner.
Some mortgage programs offer specialized financing for qualified medical professionals, while the right purchasing strategy can help you make the most of your current circumstances.
Whether you're starting residency, accepting your first attending position, relocating to California, or preparing for your next home purchase, understanding your options is the first step.
By Ronnie Jenkins, REALTOR® | Compass | Silicon Valley & South Orange CountyPublished · Last reviewed
Can Medical Professionals Buy a Home With Less Money Down?
Yes. Some lenders offer specialized mortgage programs that allow eligible medical professionals to purchase homes with low or potentially zero down payments, without traditional private mortgage insurance, and with underwriting provisions designed for medical careers.
Certain programs may also consider signed employment contracts, projected future income, or alternative treatment of student loan obligations.
However, qualifications vary by lender, profession, credit profile, employment history, income, property type, and loan amount.
Not all healthcare professionals qualify for physician mortgage programs, and specialized loans are not always the most affordable financing option.
The right approach is to compare available mortgage products and develop a purchasing strategy that fits your current finances, anticipated career path, and long-term housing needs.
Key takeaway
Your financial situation may be more complicated than that of a traditional home buyer, but you may have more purchasing options than you realize.
Where are you in your medical career?
Different Career Stages. Different Home Buying Opportunities.
Choose the stage that sounds most like you. Choosing a stage doesn't establish mortgage eligibility. It simply points you to the questions most people in your position are weighing.
Stage 01 · Match Day & Residency Relocation
Matched With a Residency Program? Let's Figure Out Where You'll Live.
Match Day is a major milestone. After years of medical school, graduates learn where they'll complete the next stage of their training.
For many, that means relocating to a new city, often with a limited amount of time to make housing decisions.
It's natural to assume renting is the only practical option. And for some residents, renting will be the right choice.
But others may benefit from exploring homeownership, particularly when their residency duration, financing eligibility, available savings, and long-term plans support the decision.
2027 Main Residency Match Day: Friday, March 19, 2027. NRMP
Key questions
- Should I rent or buy during residency?
- Can I qualify for a mortgage before starting my position?
- Are physician mortgage programs available to residents?
- How much should I spend on housing during training?
- What happens if I relocate again after residency?
Stage 02 · Residency Years 2–3
Settled Into Residency? It May Be Time to Revisit Homeownership.
After the first year or two of residency, some medical professionals have a better understanding of their location, income, lifestyle, and future plans.
They may be tired of renting or wondering whether purchasing a property makes financial sense.
However, anticipated relocation after training, modest current income, and limited savings may still make renting preferable.
Key questions
- Can I afford a home on my resident salary?
- Will student loans prevent me from qualifying?
- What down payment options might be available?
- How long do I need to own a home for buying to make financial sense?
- What if I need to sell after residency?
Stage 03 · New Attending
Starting Your First Attending Position? Your Home Buying Options May Have Changed.
Moving from residency or fellowship into an attending position can significantly change a medical professional's financial circumstances.
A new employment contract may provide greater income visibility before the first paycheck arrives. Certain lenders may consider documented future employment income when evaluating qualified borrowers.
This can create opportunities to begin the home-buying process before a new position officially starts. However, lending guidelines, verification requirements, and employment timing restrictions vary.
Key questions
- Can I buy a home using my signed employment contract?
- Do I need to wait for my first paycheck?
- How does my new salary affect mortgage qualification?
- Should I buy immediately or rent while learning the new area?
- What loan programs are available to newly appointed attending physicians?
Stage 04 · Established Professional
Established in Your Career? Make Your Next Purchase a Strategic One.
For established medical professionals, purchasing a home may involve different priorities. Rather than overcoming limited income history, buyers may be considering:
- Purchasing a larger home.
- Relocating for a new position.
- Moving closer to work.
- Buying a luxury property.
- Preserving investment assets.
- Selling one home while purchasing another.
- Evaluating jumbo mortgage financing.
- Deciding how much liquidity to preserve.
A specialized physician mortgage may still be relevant, but traditional financing could be more advantageous.
Specialized mortgage programs for medical professionals
More Options Than a Traditional Mortgage
Financing for medical professionals generally falls into five categories. The features below are examples drawn from selected programs, not guaranteed benefits for every borrower.
01
Physician Mortgage Loans
Some mortgage lenders offer specialized loans designed for eligible medical professionals. Potential program features may include:
- Low down payment requirements.
- Potentially 100% financing.
- No traditional borrower-paid private mortgage insurance.
- Higher eligible loan amounts.
- Flexible treatment of student loan obligations.
- Consideration of future employment income.
- Options for residents and fellows.
- Fixed-rate or adjustable-rate loans.
The tradeoffs to compare:
- Interest rates and APR.
- Origination fees.
- Cash reserve requirements.
- Loan limits.
- Property eligibility.
- Adjustable-rate risk.
- Total borrowing costs.
No down payment does not mean no closing costs or no financial risk.
Program examples: Newrez, Fifth Third Bank. Named for illustration only; no affiliation.
02
Conventional Mortgages
Traditional conventional financing may be more competitive for some established professionals. A borrower with strong credit, available savings, and qualifying income may find better overall terms outside a specialized medical program.
Compare complete written Loan Estimates from more than one lender, not just the advertised rate.
03
Jumbo Mortgages
Higher-priced homes in Orange County and Silicon Valley may require jumbo financing. These loans can differ in down payment requirements, reserve requirements, income documentation, credit standards, interest rates, and property eligibility.
Loan limits change by year and county, so confirm the current limit for the specific property with your lender rather than relying on a published figure.
04
California Down Payment Assistance
CalHFA MyHome Assistance Program: a deferred-payment junior loan that may help eligible first-time buyers with down payment or closing costs. Eligibility includes income limits, a qualifying CalHFA first mortgage, primary-residence requirements, and other program rules.
California Dream For All: a shared-appreciation down payment assistance program for eligible first-time, first-generation buyers. Funding is limited, vouchers are awarded through a randomized selection after a registration window, and repayment includes a share of the home's appreciation. The 2026 registration window closed March 16, 2026; check CalHFA for the current status.
These are general state programs, not programs for medical professionals, and many healthcare workers' household incomes will exceed the limits.
05
Employer and Relocation Benefits
Some healthcare employers provide relocation allowances, moving expense reimbursement, temporary housing, or other negotiated benefits.
Benefits vary by employer and may have tax or mortgage-underwriting implications. Review your employment contract and coordinate with your lender before relying on any benefit for financing.
Buying a home with a signed employment contract
Starting a New Position? You May Not Need to Wait for Your First Paycheck.
One of the challenges facing medical professionals who are relocating for a new position is the timing between accepting an offer and beginning employment.
You may have signed a contract for a well-compensated position but have limited current income documentation.
Certain specialized mortgage programs permit qualified borrowers to use projected future employment income, subject to detailed underwriting requirements.
For example, Newrez's Medical Professional Home Loan program, announced April 10, 2026, has published provisions allowing qualifying projected future income with appropriate documentation, including an offer letter, when employment begins no later than 150 days after the mortgage note date. Newrez
This is a specific program provision, not a universal mortgage qualification rule. Other lenders may have different eligibility requirements, employment timing restrictions, and documentation standards. Ronnie is not affiliated with Newrez or any lender.
What lenders may review
- Signed employment contract or offer letter.
- Salary or compensation structure.
- Employment start date.
- Professional credentials.
- Credit profile.
- Existing financial obligations.
- Student loan payments.
- Down payment and available funds.
- Cash reserves.
- Property type and intended occupancy.
What this means for buyers
A signed employment contract may allow some eligible medical professionals to begin exploring homeownership sooner. However, financing should be verified with an experienced, licensed mortgage professional before relying on projected income to enter a purchase agreement.
Let's review your purchase timeline and connect the real estate strategy with appropriate financing guidance.
How student loans affect home buying
Significant Student Debt Doesn't Automatically Mean You Can't Qualify.
Medical professionals may carry substantial education debt even as their earning potential increases. Mortgage qualification generally considers applicable debt obligations relative to qualifying income.
However, different loan programs may calculate student loan obligations differently. Student loans are not ignored or automatically discounted in physician mortgage programs; each program applies its own guidelines.
Income-driven repayment plans
Some programs may use a documented income-driven payment, which can be lower than a standard amortizing payment.
Actual documented monthly payments
What appears on your credit report and loan statements is often the starting point.
Deferred student loans
Deferred or forbearance loans may still be counted using a calculated payment, depending on the program.
Program-specific debt calculations
Conventional guidelines and specialized medical programs can treat the same loan differently.
Debt-to-income ratios
Your total monthly obligations, including the new housing payment, are compared to qualifying income.
Available reserves
Savings left after closing can matter as much as the down payment.
The amount of student loan debt matters, but the way a lender evaluates the applicable monthly obligation can also affect qualification.
Financial readiness is different from mortgage qualification. A lender may approve an amount that is not appropriate for your overall financial situation, especially while student loan payments are still a large part of your monthly budget. Conventional guidelines: Fannie Mae Selling Guide.
Rent or buy during residency?
Homeownership Isn't Always the Right Answer. Here's How to Decide.
For residents and fellows, the honest answer is often “it depends on how long you'll stay.” Here's a balanced way to think it through.
Reasons renting may make more sense
- Residency duration is relatively short.
- Another relocation is likely.
- Down payment or emergency savings are limited.
- Renting provides desired flexibility.
- Local homeownership costs are high.
- You're uncertain about your long-term plans.
- Expected transaction costs outweigh potential ownership benefits.
Reasons buying may be worth exploring
- You expect to remain in the community for several years.
- Financing terms and monthly costs are sustainable.
- Sufficient emergency reserves will remain.
- The property meets longer-term needs.
- Ownership is compatible with likely career changes.
- The overall economics compare favorably with renting.
A realistic cost comparison
Renting
Monthly rent · Renters insurance · Moving costs · Flexibility to leave at lease end
Owning
Mortgage principal and interest · Property taxes · Homeowners insurance · HOA dues · Maintenance · Purchase closing costs · Potential selling costs · Market risk
The equity-building portion of a mortgage payment is not an immediate financial gain. Property values can decline, buying and selling involve transaction costs, and short holding periods may not justify purchasing.
Illustrative tool
Rent vs. Buy During Residency
Enter your own numbers. Starting values are placeholders, not local estimates, and the price change defaults to 0% because appreciation is never guaranteed.
Total rent over 3 yr
$108,000
Unrecoverable cost of owning
$300,718
Interest $163,918 · taxes, insurance, HOA, upkeep $64,800 · buying $18,000 · selling $54,000
In this scenario
Renting costs about $192,718 less
Monthly principal + interest: $5,404
Assumes a 30-year fixed loan. Principal repaid is treated as your own money returned at sale, not a cost or a gain. Ignores rent increases, mortgage insurance, tax effects and what your down payment could earn elsewhere. For illustration only; not financial advice.
Relocating for a new medical position
A New Position. A New City. A Smart Plan for Your Next Home.
Medical professionals often have to make important housing decisions within a compressed period after accepting a position, sometimes from another state, and often while finishing training.
- Researching a new city remotely
- Choosing a suitable neighborhood
- Evaluating actual commute routes
- Understanding local property values
- Comparing renting and buying
- Coordinating mortgage approval with employment
- Reviewing employer relocation assistance
- Purchasing before beginning a new role
- Remote property tours
- Inspections and due diligence
- Managing relocation and closing timelines
Five Steps to a Successful Medical Relocation
Step 1
Confirm employment and timing
Review the offer or employment contract, expected start date, and relocation requirements.
Step 2
Establish a realistic housing budget
Work with a lender to understand eligible financing and determine a comfortable monthly ownership budget.
Step 3
Understand the local market
Compare available properties, neighborhoods, pricing, and ownership costs.
Step 4
Develop a purchase or rental strategy
Determine whether buying immediately is appropriate or whether renting temporarily provides meaningful benefits.
Step 5
Coordinate the move
Align employment, travel, property tours, inspections, financing, closing, and possession.
Buying in Orange County
Finding the Right Home in South Orange County
South Orange County offers a wide range of community types, from master-planned villages to coastal neighborhoods. Commutes depend on the specific route, time of day, and where you'll work, so we test them rather than estimate them.
Irvine
A diverse range of residential villages, property types, and access to major Orange County employment corridors.
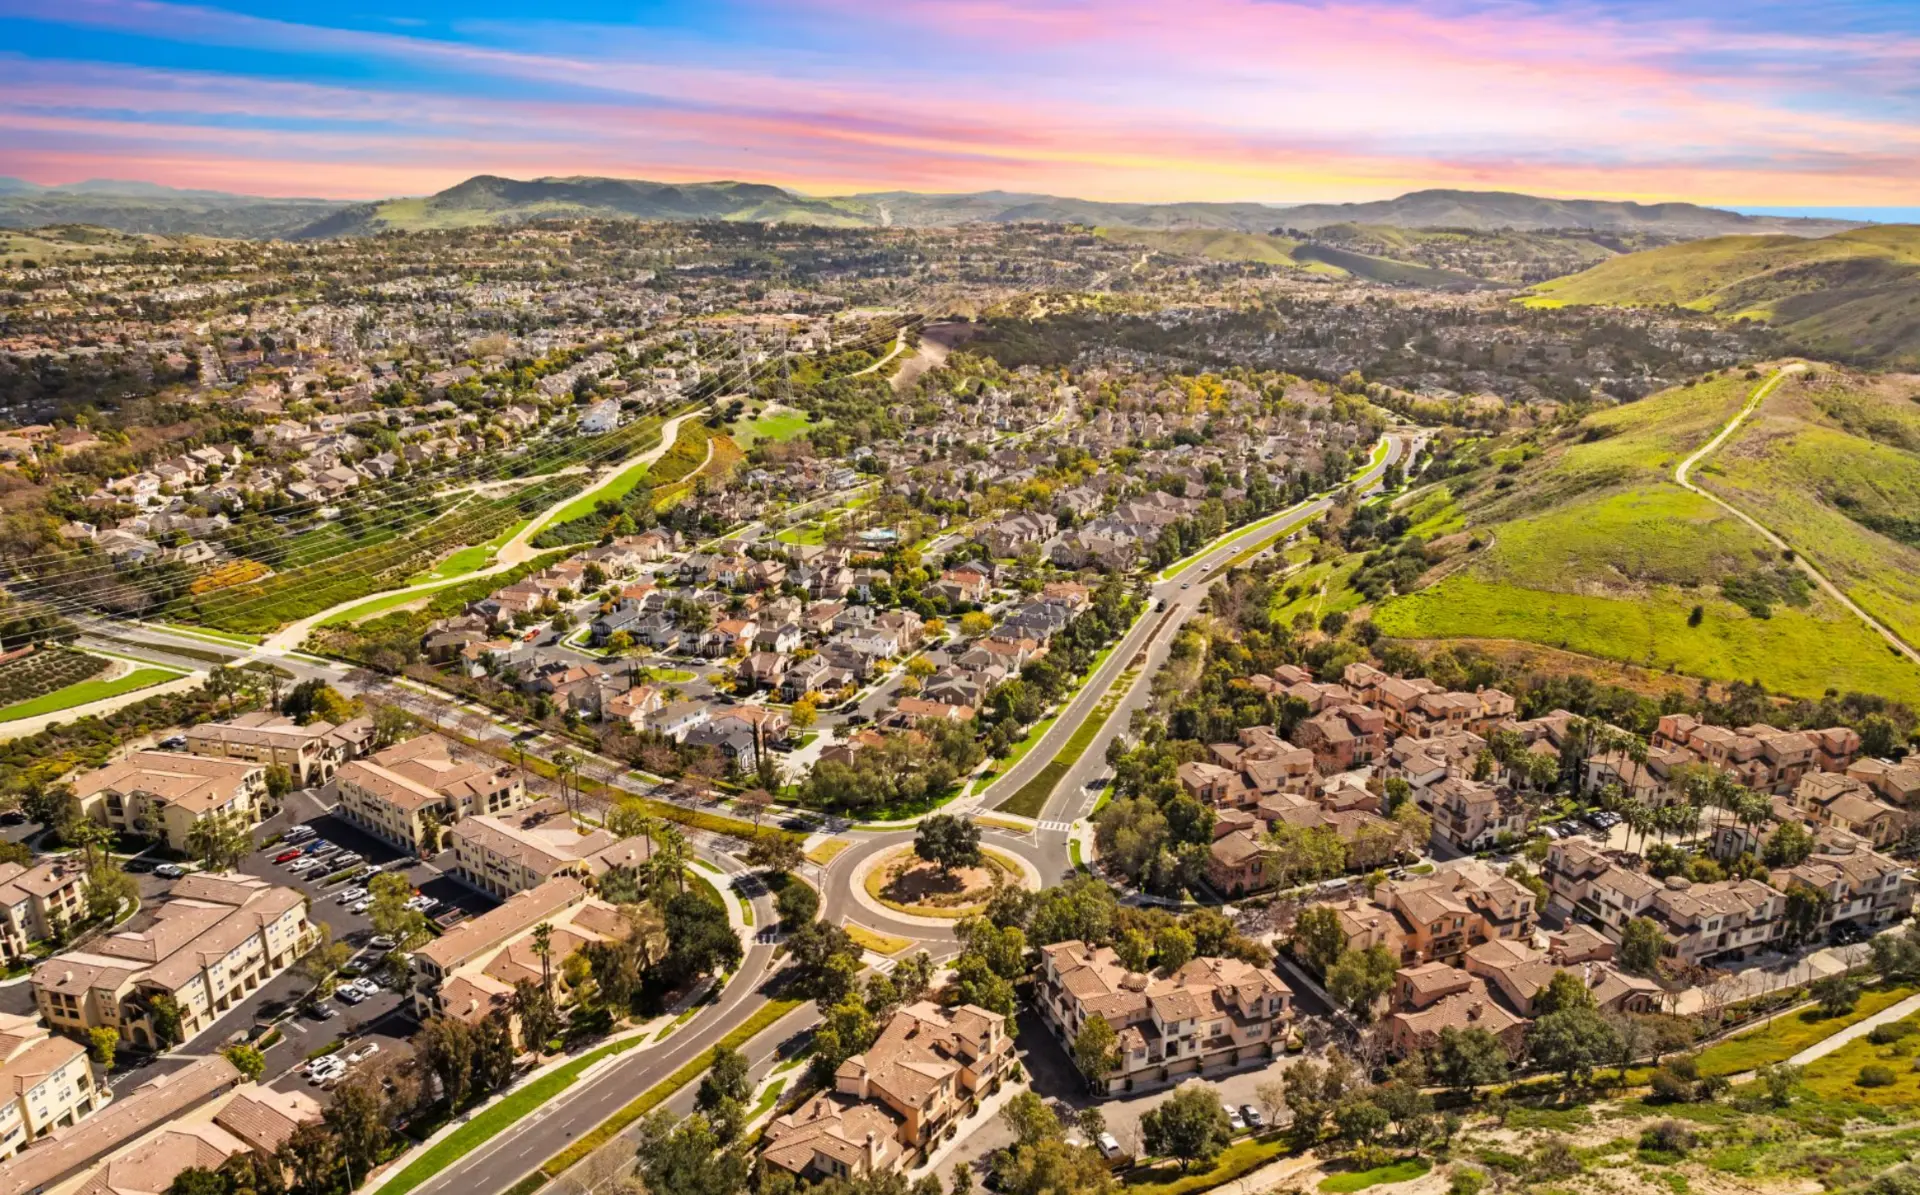
Ladera Ranch
Master-planned neighborhoods with community amenities, parks, trails, and a range of home styles.
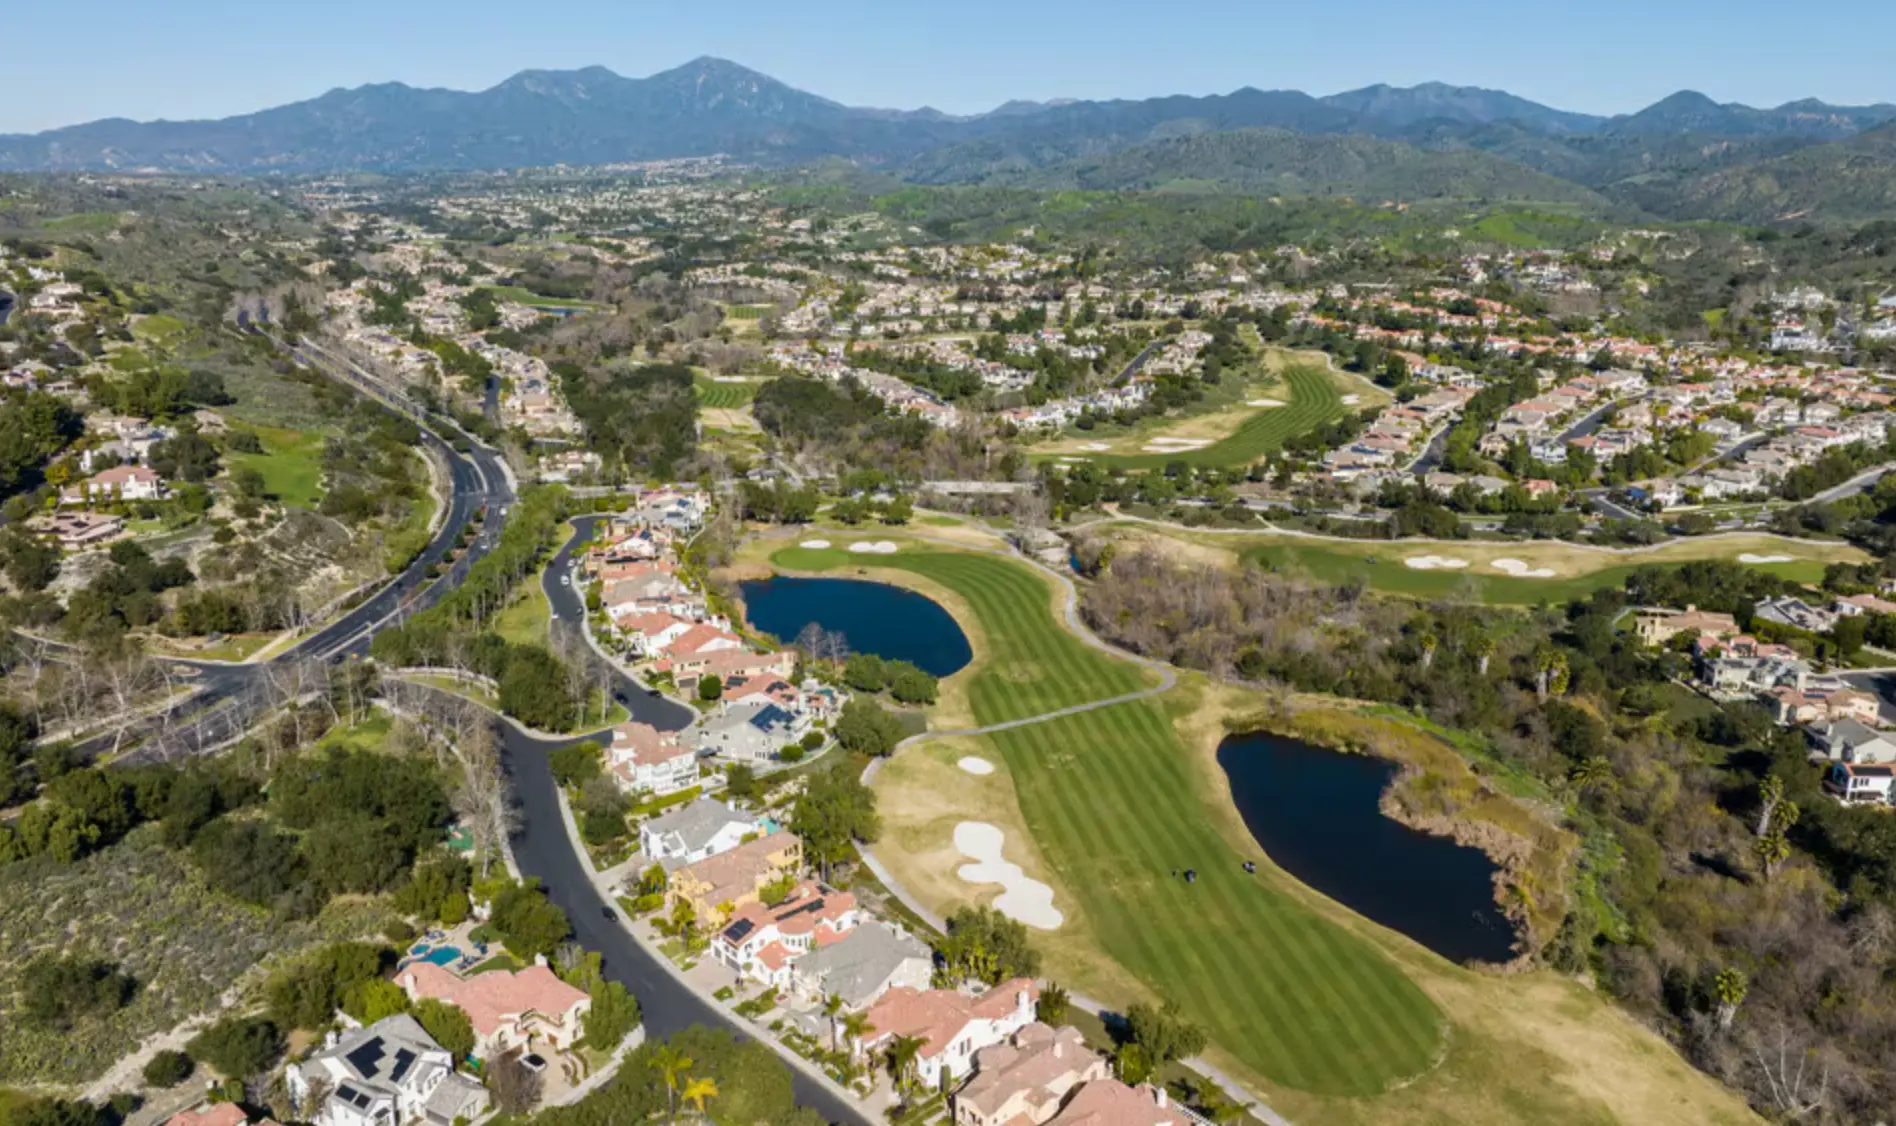
Mission Viejo and Laguna Niguel
Established residential neighborhoods with varied property styles, lot characteristics, and local amenities.
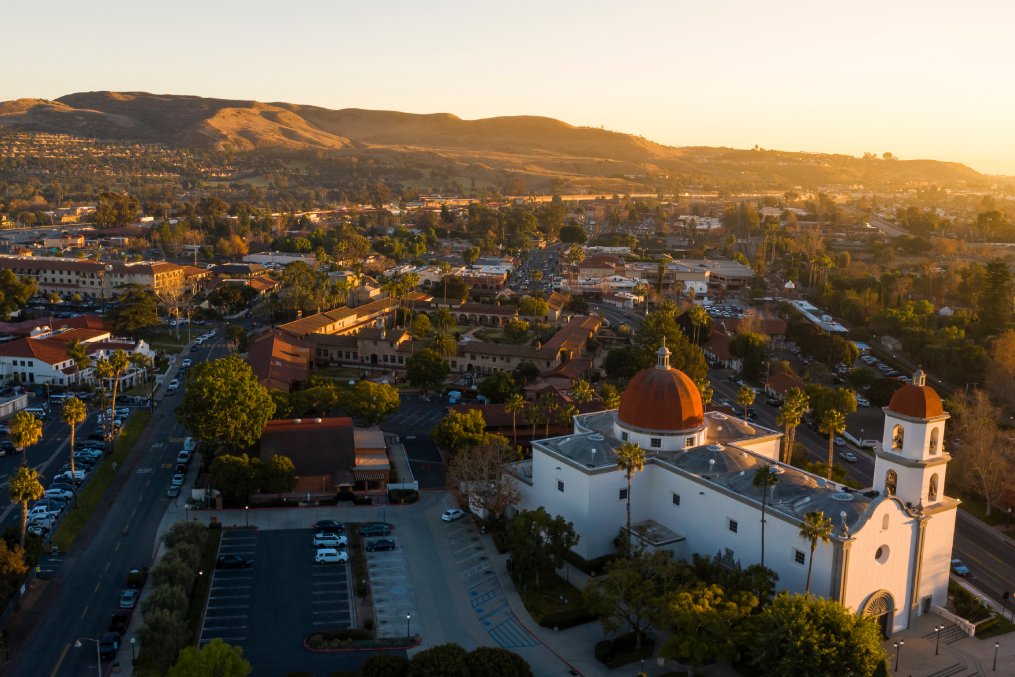
San Juan Capistrano
Historic character, established neighborhoods, and newer residential communities.
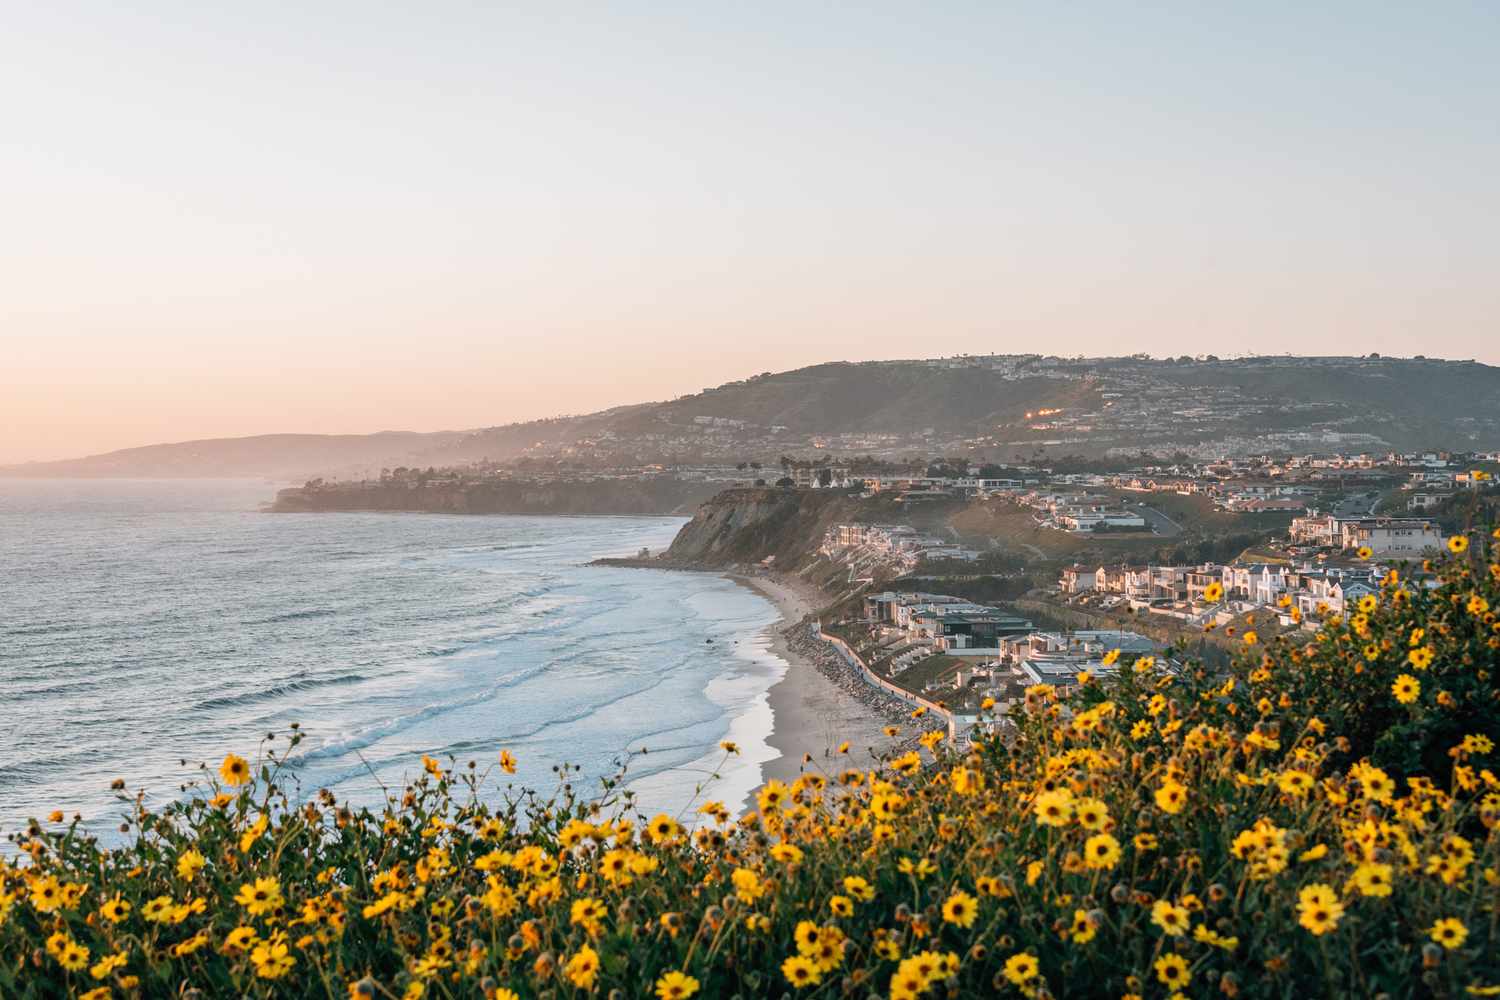
Dana Point and San Clemente
Coastal neighborhoods, established residential properties, and a wide range of price points.
San Clemente guide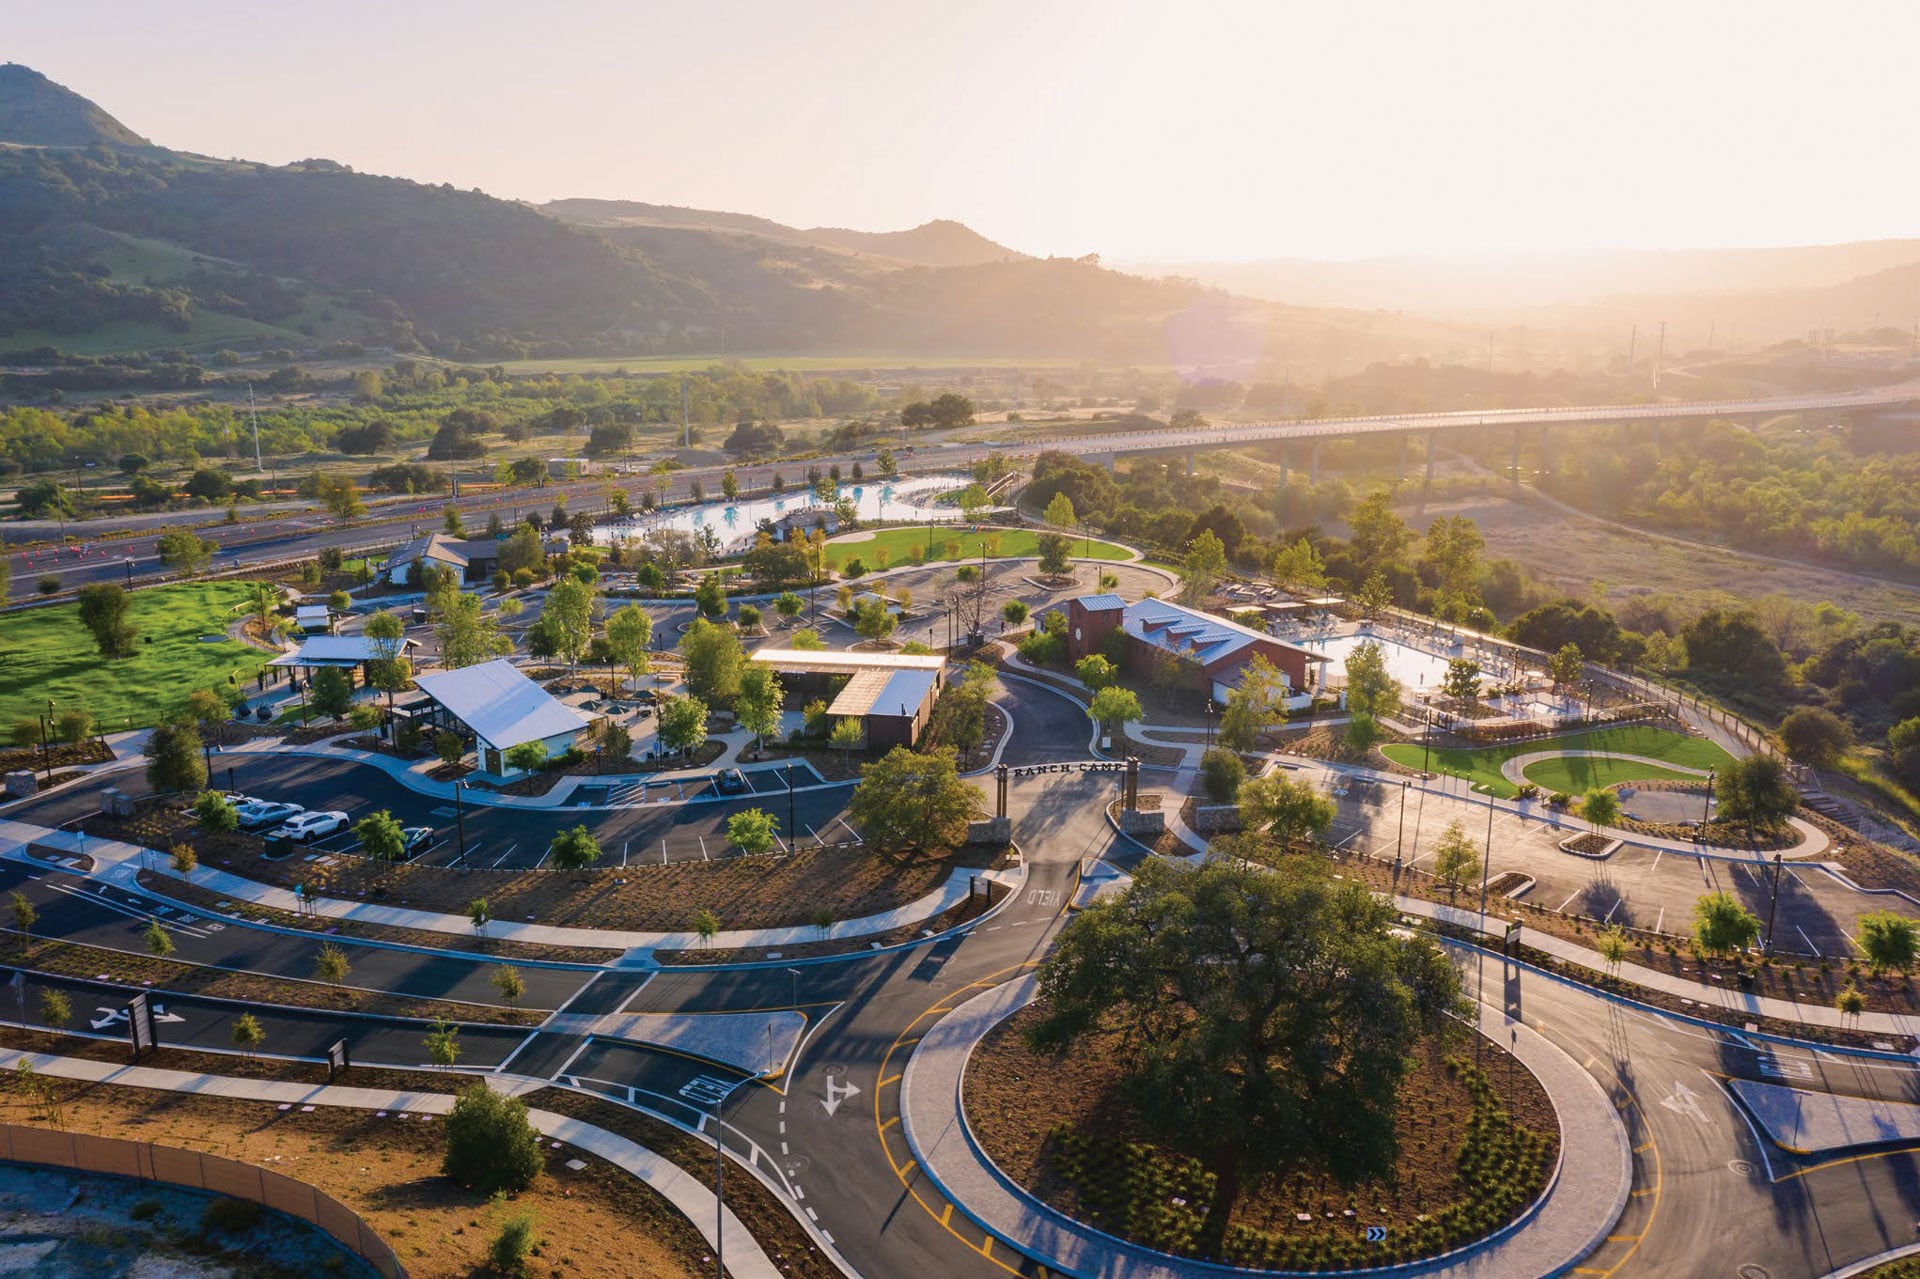
Rancho Mission Viejo
Newer master-planned residential neighborhoods with community amenities and varying ownership costs.
Important ownership considerations
- Property taxes
- Based on purchase price, plus any voter-approved assessments.
- HOA dues
- Common in planned communities; review what they cover and the association's reserves.
- Mello-Roos
- Special tax assessments in many newer communities can add meaningfully to annual costs.
- Insurance
- Coverage availability and premiums vary by property and location; get quotes early.
- Housing age and maintenance
- Older homes may need more near-term investment.
- Location relative to work
- Drive the route at the hours you'll actually commute.
- Ownership versus rental flexibility
- Match the decision to how long you expect to stay.
Buying in Silicon Valley
Finding the Right Home in Silicon Valley
Silicon Valley's neighborhoods vary block by block. Jumbo financing is common, much of the housing stock is older, and condition, lot and school boundaries can move value significantly. Confirm school assignments directly with the district for any specific address.
Featured
Los Gatos
Historic downtown character, established neighborhoods, foothill surroundings, and property-specific pricing considerations.
Willow Glen
Established residential streets and homes with distinctive architectural character.
Cambrian
A range of established neighborhoods and housing styles.
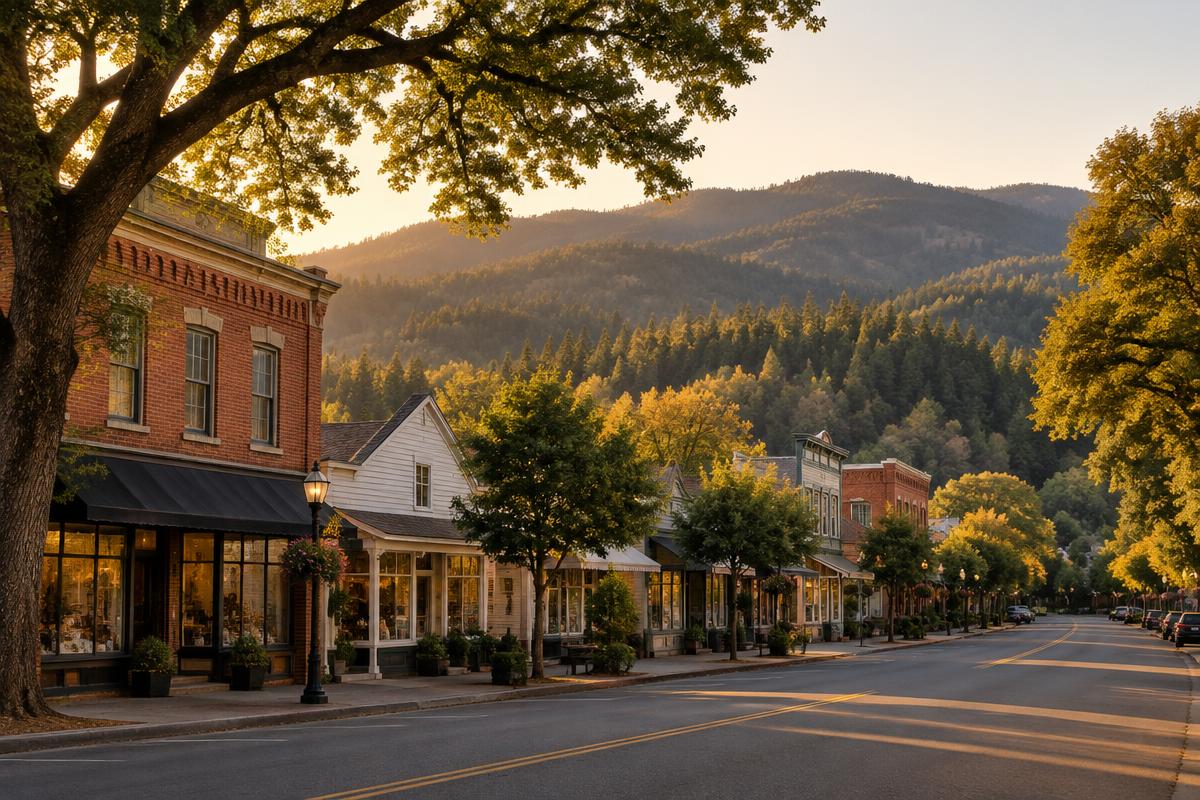
Saratoga
Luxury properties, foothill settings, and substantial variation in lot sizes and individual home characteristics.
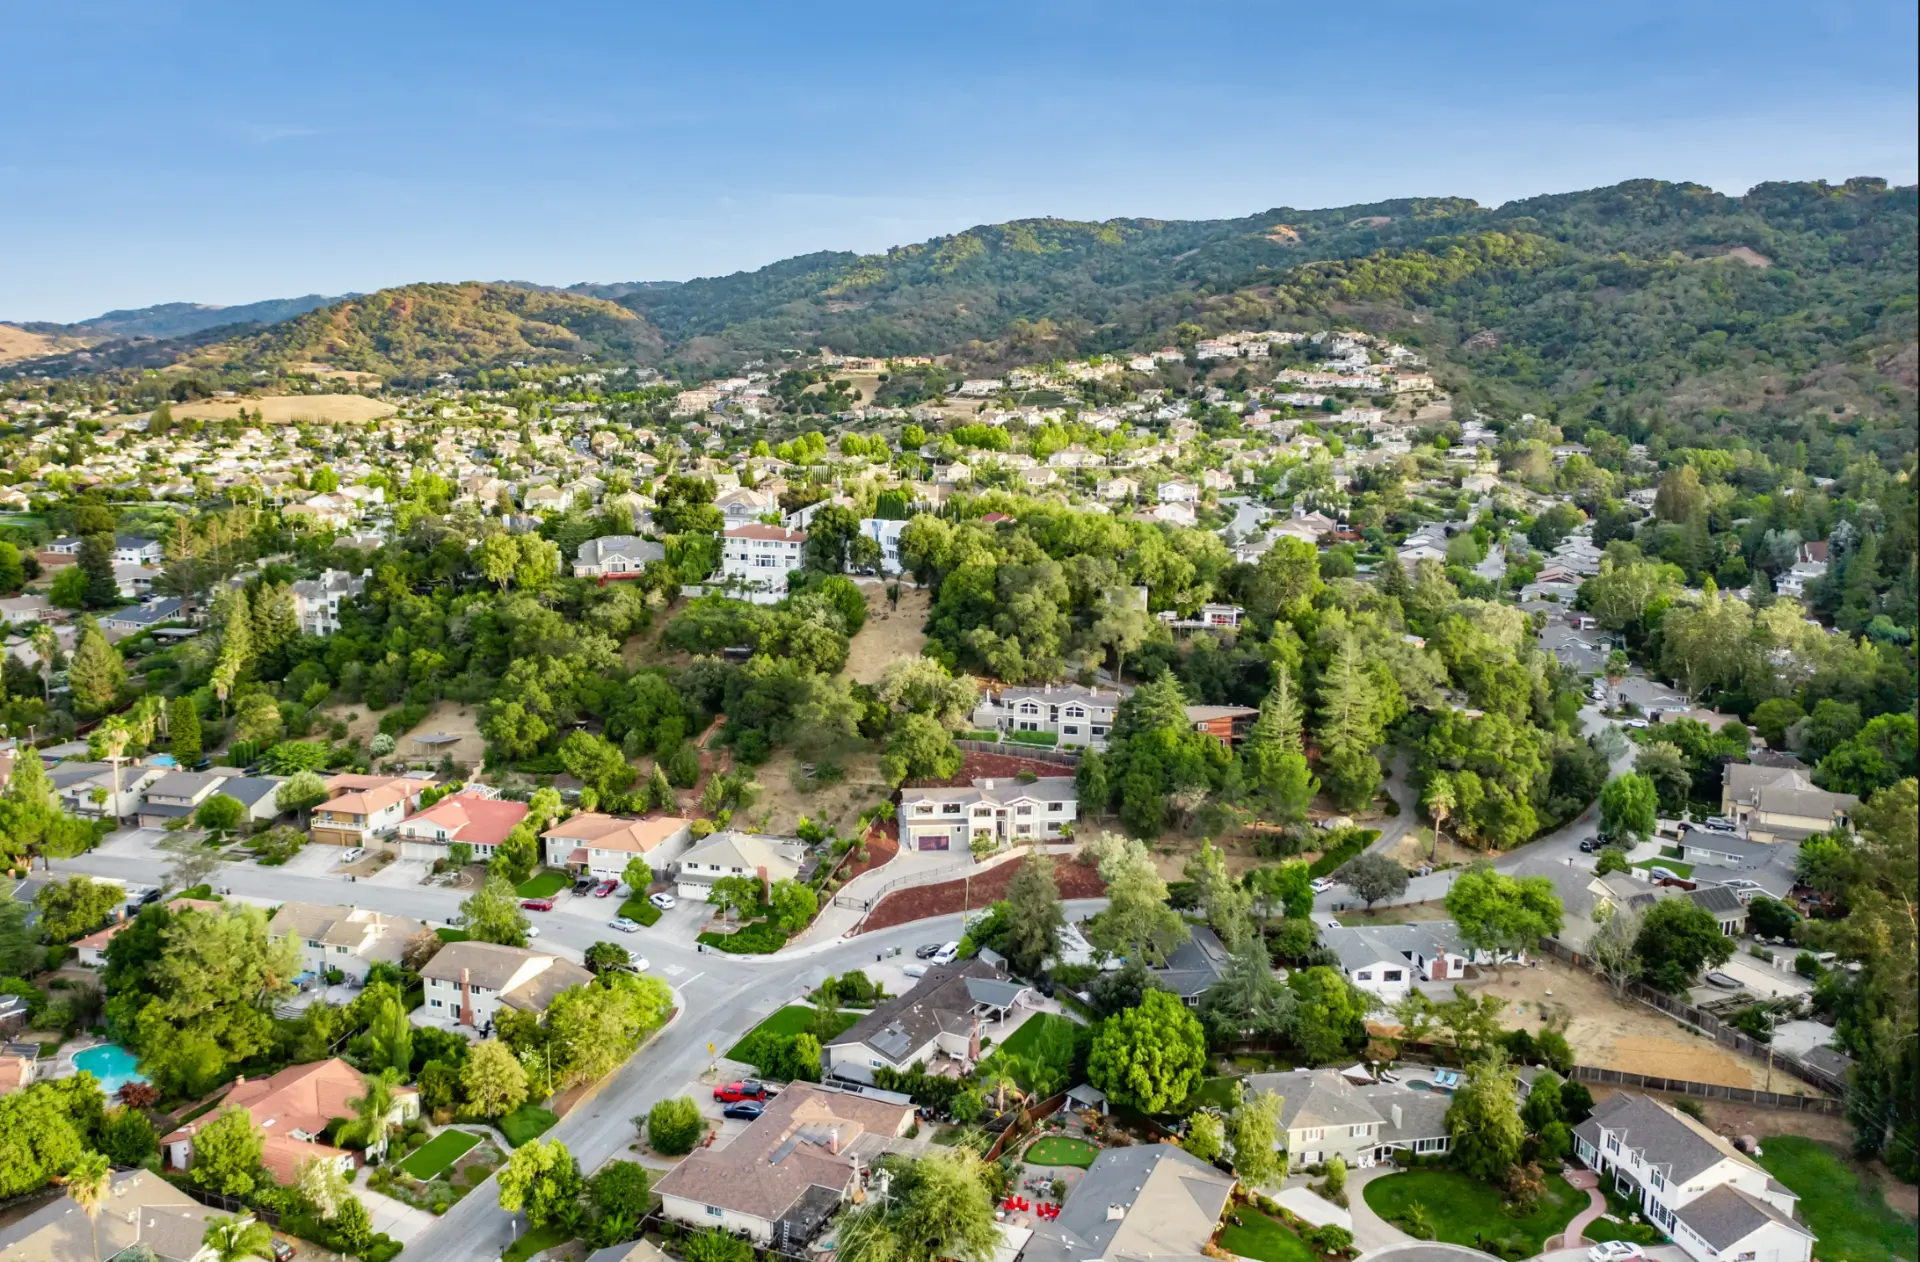
Almaden Valley
Established neighborhoods near open space and outdoor recreation.
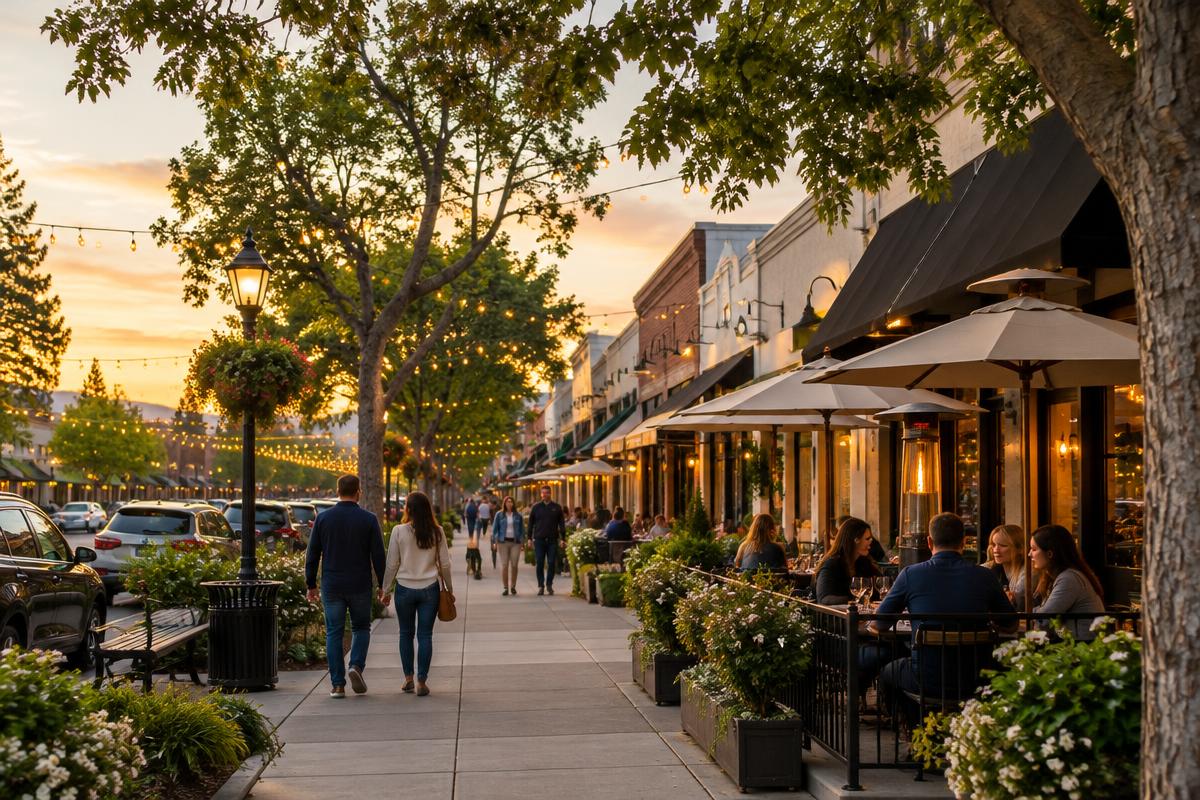
Campbell
Residential variety, an established downtown, and access to major employment corridors.
Rose Garden
Historic neighborhood character and architectural diversity.
- Jumbo financing
- Reserve, down payment and documentation standards often differ from conforming loans.
- Older housing stock
- Many homes date from the mid-20th century or earlier.
- Inspections
- Pre-offer and contingency inspections deserve real attention: foundation, sewer lateral, roof, electrical.
- School boundaries
- Boundaries don't always follow city lines; verify for each address.
- Property condition
- Updated and original homes on the same street can price very differently.
- Localized price differences
- Neighborhood-level, not citywide, pricing drives smart offers.
A smarter home buying strategy for medical professionals
Qualifying for a Mortgage and Affording a Home Are Two Different Things.
Medical professionals may have substantial earning potential, but housing decisions should be based on sustainable cash flow, not future income expectations alone.
01
Preserving liquidity
A lower down payment may help preserve cash, but can result in a larger mortgage and higher borrowing costs.
02
Planning around career changes
Residency completion, new attending roles, fellowship transitions, and practice changes may affect future housing requirements.
03
Comparing total financing costs
Review rate, APR, lender fees, mortgage insurance, points, cash reserves, and overall borrowing costs.
04
Managing student loan obligations
Understand the impact of student loan payments on household cash flow.
05
Purchasing the right property
Prioritize location, property condition, functionality, ownership costs, and anticipated length of ownership.
06
Coordinating with financial professionals
Mortgage professionals handle financing eligibility. Tax professionals and financial advisors can provide guidance within their areas of expertise.
The smartest home purchase isn't necessarily the most expensive home you can qualify for. It's the home that supports your career, lifestyle, and financial future.
Home Buying Programs: Side-by-Side Comparison
General characteristics only. No rates, maximum loan amounts or universal eligibility are implied; terms vary by lender and change over time.
Physician / Medical Professional Mortgage
- Typical eligible buyer
- Physicians and, at some lenders, dentists and other designated medical credentials, including some residents and fellows.
- Possible down payment
- Low or, at some lenders, potentially 100% financing.
- Student debt
- Some programs use flexible calculations; debt is not ignored.
- Employment documentation
- Some accept a signed contract or offer letter with start-date limits.
- Mortgage insurance
- Often no traditional borrower-paid PMI; costs may appear elsewhere.
- Major limitations
- Profession, lender, loan amount, property and reserve restrictions.
- Ask the lender
- Which credentials qualify? How are my student loans calculated? Compare the APR to a conventional quote.
Conventional Mortgage
- Typical eligible buyer
- Broad eligibility for qualified borrowers.
- Possible down payment
- Varies by program and borrower profile.
- Student debt
- Calculated under standard guidelines.
- Employment documentation
- Typically documented current income and history.
- Mortgage insurance
- Usually required below 20% down.
- Major limitations
- Standard underwriting may not fit early-career income.
- Ask the lender
- How do the total costs compare with a specialized program?
Jumbo Mortgage
- Typical eligible buyer
- Buyers of higher-priced homes above conforming limits.
- Possible down payment
- Lender-specific; often larger than conforming.
- Student debt
- Standard or lender-specific treatment.
- Employment documentation
- Often fuller documentation and stronger credit.
- Mortgage insurance
- Varies by lender.
- Major limitations
- Higher reserve and credit standards.
- Ask the lender
- What reserves will I need after closing?
CalHFA Assistance
- Typical eligible buyer
- Qualifying first-time buyers (Dream For All also requires first-generation status) within income limits.
- Possible down payment
- Assistance paired with a qualifying CalHFA first mortgage.
- Student debt
- Counted under the first-mortgage guidelines.
- Employment documentation
- Standard documentation for the first mortgage.
- Mortgage insurance
- Depends on the first mortgage.
- Major limitations
- Income limits, limited funding, primary residence, repayment terms.
- Ask the lender
- Do I meet the current county income limit? Is funding available?
VA Mortgage
- Typical eligible buyer
- Eligible service members and veterans, including qualified medical professionals with military service.
- Possible down payment
- May allow no down payment for eligible borrowers.
- Student debt
- Counted under VA guidelines.
- Employment documentation
- Standard VA documentation.
- Mortgage insurance
- No monthly PMI; a funding fee may apply.
- Major limitations
- Service eligibility and occupancy requirements.
- Ask the lender
- How does my entitlement apply to this price?
A medical professional mortgage is one option, not necessarily the best option. Comparing the complete financial picture is essential.
Ronnie's perspective
Your Career Is Unique. Your Real Estate Strategy Should Be Too.
Medical professionals often face a very different home-buying journey from the average buyer.
You might have strong earning potential but significant student loans. You may be relocating for a new position or trying to purchase before your first paycheck arrives.
For some, specialized mortgage programs open doors that traditional financing may not. But finding the right loan is only part of the equation. The bigger question is how to make the right real estate decision at the right stage of your career.
I've spent more than 14 years helping clients navigate competitive California real estate markets, and my approach is always the same: understand the circumstances, explore the options, and develop a strategy that makes sense.
Whether you're buying your first home or relocating for your next professional opportunity, my goal is to make the process more informed, more manageable, and ultimately more successful.
Ronnie JenkinsREALTOR® | Compass14+ Years of California Real Estate ExperienceSilicon Valley & South Orange CountyCalifornia DRE #01922959
Ronnie is a real estate advisor, not a mortgage loan originator. Financing eligibility is determined by licensed mortgage professionals.
More about RonnieFrequently Asked Questions About Home Buying for Medical Professionals
Can doctors buy a home with no down payment?
Certain specialized physician mortgage programs may offer 100% financing for qualified borrowers. Requirements vary by lender, profession, loan amount, credit profile, and property eligibility. A zero-down option does not eliminate closing costs, reserves, or other borrowing obligations.
Can I buy a house before starting my first attending position?
Some lenders may consider a signed employment contract and qualifying projected income. Documentation requirements and permitted employment start dates vary. Verify eligibility before committing to a purchase.
Can residents qualify for a physician mortgage?
Certain programs include eligible residents and fellows. However, loan amounts, income requirements, employment verification, and other conditions vary.
Should I rent or buy during residency?
It depends on expected time in the community, monthly costs, available savings, financing terms, and likely future relocation. Shorter anticipated ownership periods may favor renting because purchasing and selling involve substantial transaction costs.
How do student loans affect physician mortgage qualification?
Different lending programs evaluate student loan obligations according to their underwriting guidelines. Some specialized programs offer flexibility, but student loan debt is not universally excluded from qualification.
Are physician mortgages better than conventional loans?
Not necessarily. Specialized programs may offer benefits such as lower down payments or different underwriting, while conventional loans may provide more favorable rates or total costs for certain borrowers. Compare complete loan terms.
Can dentists qualify for physician mortgages?
Many specialized programs include eligible dentists, although the requirements differ by lender.
Do nurses qualify for medical professional mortgage programs?
Some broader programs may include certain nursing professions, while others are restricted to physicians and designated medical credentials. Nurses should also explore conventional financing and applicable assistance programs.
Can I buy a house using an offer letter from a hospital?
Some lenders may accept qualifying employment documentation, including a signed offer letter or contract, subject to income, timing, and underwriting restrictions.
Can I buy a home in California while living in another state?
Yes, it is possible to purchase a property while living elsewhere, subject to financing, transaction, and occupancy requirements. Remote tours and other technology can help, but appropriate property due diligence remains essential.
How much should a new attending physician spend on a home?
There is no universal answer. A sustainable budget considers take-home income, student loan obligations, savings, property taxes, insurance, maintenance, and other financial commitments.
Are there down payment assistance programs for California medical professionals?
Medical professionals who meet the eligibility requirements may qualify for general California assistance programs. These programs may have income limits, first-time buyer requirements, funding restrictions, and other conditions.
Do physician mortgages require PMI?
Some specialized physician mortgages do not require traditional borrower-paid private mortgage insurance. However, financing costs may be reflected elsewhere in the loan terms.
Can medical professionals qualify for jumbo loans?
Yes, eligible medical professionals may qualify for jumbo financing, subject to lender standards, income, credit, assets, and property requirements.
What should I do after Match Day if I'm relocating?
Start by evaluating your employment start date, housing budget, expected time in the area, rental options, and potential eligibility for specialized financing. Do not assume purchasing is always preferable to renting.
Sources and Further Reading
- Newrez, Newrez Launches Medical Professional Home Loan. Published .Lender press release; program terms are specific to Newrez and may change.
- Fifth Third Bank, Physician LoanExample of a lender physician program; confirm availability for California properties.
- California Housing Finance Agency, MyHome Assistance Program
- California Housing Finance Agency, California Dream For All Shared Appreciation Loan2026 registration ran February 24 to March 16, 2026 (CalHFA Program Bulletin #2026-01).
- National Resident Matching Program, 2027 Main Residency Match CalendarMatch Day: Friday, March 19, 2027. Re-verify each year.
- Consumer Financial Protection Bureau, Owning a Home: comparing Loan Estimates
- Fannie Mae, Selling Guide (conventional underwriting, including student loan payment calculation)
This guide is general education, not mortgage, tax or legal advice, and not an offer to lend. Ronnie Jenkins is a REALTOR® with Compass, not a mortgage loan originator, and has no affiliation with any lender named here. Program terms change; verify with a licensed mortgage professional. Last reviewed .