Palisades Fire | Housing & Relocation Guide
Palisades Fire Housing Assistance Is Running Out. What Happens Next?
For many families displaced by the January 2025 Palisades Fire, the question is no longer just when they can return home. It's what to do next.
As temporary housing assistance ends and insurance benefits are exhausted, homeowners face difficult decisions about rebuilding, selling, continuing to rent, or starting over somewhere new.
If you've been living in Orange County since the fires, you may also be asking a different question: Could this become your permanent home?
Explore your options, understand the important deadlines, and plan your next move with greater clarity.
By Ronnie Jenkins | REALTOR® at CompassUpdated November 2026 · Last reviewed
Is Temporary Housing Assistance Ending for Palisades Fire Victims?
Yes, some temporary housing assistance has ended, while other benefits may still be available. FEMA's extended rental-assistance period for eligible renters affected by the January 2025 Los Angeles wildfires ended October 9, 2026. Eligible homeowners may receive FEMA assistance through July 9, 2027.
Private homeowners' insurance is different. Additional Living Expense (ALE), also known as Loss of Use coverage, generally has a minimum 24-month period following a covered declared disaster, with extensions available under qualifying circumstances. However, policy dollar limits can be exhausted sooner.
There is no single October deadline that applies to every fire victim's insurance coverage.
FEMA and insurance are separate programs.
FEMA's Individuals and Households Program is federal disaster assistance with its own eligibility rules and deadlines. ALE is a benefit of your private insurance policy. One ending does not end the other.
The 24-month mark arrives in January 2027.
The Palisades Fire began in January 2025, so the minimum 24-month ALE period for many homeowners reaches its anniversary in January 2027. Whether you qualify for more time depends on your policy and your rebuilding circumstances.
Confirm your remaining benefits with your insurer.
Ask your insurer, in writing, how much ALE remains in dollars and in time, and what documentation an extension request requires. Renters' policies often provide ALE for a shorter period than homeowners' policies.
| Housing assistance | Important information | ||
|---|---|---|---|
| Federal · FEMA | Federal · FEMAFEMA assistance for eligible renters | Extended through October 9, 2026Source | Source |
| FEMA assistance for eligible homeowners | Extended through July 9, 2027Source | Source | |
| Private · Your policy | Private · Your policyHomeowners' insurance ALE | Generally at least 24 months following a covered declared disaster, subject to policy termsSource | Source |
| ALE extension | Up to 12 additional months for qualifying reconstruction delays, plus six-month extensions for good causeSource | Source | |
| Individual dollar limits | Benefits can be exhausted before the maximum time periodSource | Source |
If you are registered with FEMA and still need temporary housing help, call the FEMA Helpline at 800-621-3362 or update your application at DisasterAssistance.gov. Sources: Office of the Governor, Cal OES, California Department of Insurance.
Nearly Two Years Later, Many Families Still Haven't Returned Home
- of surveyed fire survivors had not returned home.
- Two-thirds
- of surveyed fire survivors had not returned home.
- of surveyed survivors who lost their homes entirely had returned.
- 1%
- of surveyed survivors who lost their homes entirely had returned.
- of surveyed survivors reported financial difficulties resulting from the fires.
- Nearly 80%
- of surveyed survivors reported financial difficulties resulting from the fires.
- had sold, were selling, or planned to sell their property, up from 7% in June.
- 11%
- had sold, were selling, or planned to sell their property, up from 7% in June.
Findings from the Department of Angels' survey of more than 2,000 fire-impacted residents across Pacific Palisades, Altadena, Malibu and Pasadena, conducted August 25 to September 8, 2026. They are not limited to Palisades homeowners. Department of Angels, October 21, 2026.
For many homeowners, rebuilding has become a longer and more expensive process than anticipated. Insurance disputes, construction costs, permitting challenges and the ongoing expense of temporary housing have left families balancing financial and emotional decisions.
Some remain committed to rebuilding. Others are beginning to explore whether selling and purchasing another property might offer a more practical path forward.
Neither decision should be made without understanding the financial implications.
Most survivors in the survey had not sold or decided to sell. The share choosing to sell has grown, while the share still undecided has fallen.
Four Paths Forward for Displaced Homeowners
There is no universally right answer. Each path below comes with its own costs, timelines and trade-offs, and many families move between them as their situation becomes clearer.
Option 01
Rebuild and Return
For families committed to returning to their original neighborhood.
- Map the realistic rebuilding timeline, including design, permitting and construction, against the insurance benefits that remain.
- Model cash flow month by month: mortgage on the original property, temporary rent once ALE ends, and construction draws.
- Get current construction estimates and compare them with your dwelling coverage and any extended replacement cost.
- Coordinate your temporary housing lease with the projected move-in date, with room for delays.
Option 02
Continue Renting
For homeowners who need additional time before making a permanent decision.
- Furnished short-term rentals usually cost more per month than a traditional 12-month unfurnished lease, but offer flexibility.
- Once subsidies or ALE end, compare the full monthly burden: rent, the existing mortgage, property taxes and insurance on the original property.
- A longer lease can buy time to decide without forcing a rushed purchase or sale.
Option 03
Sell and Start Again
For homeowners exploring the sale of their damaged property or land.
- Understand what the property or lot is worth in its current condition, and what buyers in that market are paying.
- Account for the existing mortgage, any liens, and how a sale may interact with insurance claims that are still open.
- Consider sale timing and potential tax implications, including capital gains and Proposition 19.
- Get independent legal, insurance and tax guidance before you commit. Ronnie is a REALTOR®, not an insurance attorney, public adjuster or tax advisor.
Option 04
Purchase a New Home
For families ready to establish stability in a new community.
- Evaluate affordability with your lender, including whether you can qualify while still carrying the original property.
- Weigh timing: buying before, during or after the sale of your Los Angeles property each changes your financing and tax picture.
- Think through lifestyle: coast or inland, walkable village or planned community, commute and daily routines.
- Look at the financial relationship between the two properties as one plan, not two separate transactions.
Exploring a move to Orange County? Let's talk through what that could look like.
Start the conversation
A New Chapter in Orange County
You Came to Orange County Temporarily. What If You Stayed?
When the Palisades Fire forced families from their homes, some found temporary housing in Orange County.
What began as an unexpected relocation may have become something more familiar. New routines, favorite neighborhoods, local friendships, schools, activities and a different pace of life.
Now, as temporary housing arrangements come to an end, some families are considering whether to return to Los Angeles or put down permanent roots in Orange County.
It's a significant decision, especially when it wasn't part of the original plan.
Whether you're considering staying in your current community, exploring another part of Orange County, or simply weighing your options, understanding the local real estate market is an important first step.
From Temporary Housing to a Permanent Home
Should we buy the home we're currently renting?
Sometimes it makes sense, and you already know the home and the street better than any buyer could from a showing. Ask the owner directly whether they would consider selling. Then treat it like any other purchase: independent comparable sales, a full inspection, insurance quotes and HOA documents. Your rent is not a guide to the price, and a friendly landlord relationship is not a reason to skip due diligence.
Which Orange County community feels most like what we loved about the Palisades?
Start by naming what you valued: a village center you could walk to, proximity to the ocean, canyon or hillside settings, a tight-knit neighborhood, or a particular kind of home. Coastal towns such as Laguna Beach, Dana Point and San Clemente offer ocean-oriented living with their own village character. Planned communities such as Ladera Ranch and Rancho Mission Viejo trade that for parks, trails and amenities. No Orange County community is a replacement for the Palisades, but several may fit the way you want to live.
Would purchasing in Orange County make financial sense compared with rebuilding?
Compare the two as complete scenarios. For rebuilding: current construction estimates, insurance proceeds still available, the timeline, and the cost of renting until you move back. For buying: what the Los Angeles property could sell for in its current condition, the purchase price and ongoing costs in Orange County, and any tax effects. A financial advisor and tax professional should review the numbers with you.
How do we buy before our Los Angeles property is sold?
Options can include qualifying with both housing costs, using other assets or a bridge loan, or making an offer contingent on a sale, which is usually less competitive. If you plan to use Proposition 19 and buy the replacement home first, the Board of Equalization notes that you pay property taxes on the replacement home's full value until the original property sells. Talk to a lender early so the order of transactions is a choice, not a surprise.
What if we're unsure whether to stay permanently?
Renting longer can be the right strategy. Buying and selling both carry real transaction costs, so a purchase works best when you expect to stay several years. A 12-month lease in the community you're considering lets you test schools, commutes and daily life before committing, and gives insurance and rebuilding questions time to resolve.
How will property taxes, insurance and ongoing ownership costs compare?
Under Proposition 13, the base property tax rate is 1% of assessed value, plus voter-approved bonds and any special taxes, which vary by parcel. Many South Orange County communities add HOA dues and, in newer areas, Mello-Roos (Community Facilities District) taxes. Insurance availability and premiums vary by property. If you qualify for a Proposition 19 base year value transfer, your property tax picture may look very different, so verify eligibility before you compare.
For some families, renting longer is the right answer. A good plan should make room for that.
Finding Your Place in Orange County
South Orange County is not one place. Its communities differ in setting, housing, ownership costs and daily rhythm, and the right fit depends far more on how you want to live than on any ranking. Here is a starting point, with links to Ronnie's full community guides.
Coastal village
Laguna Beach
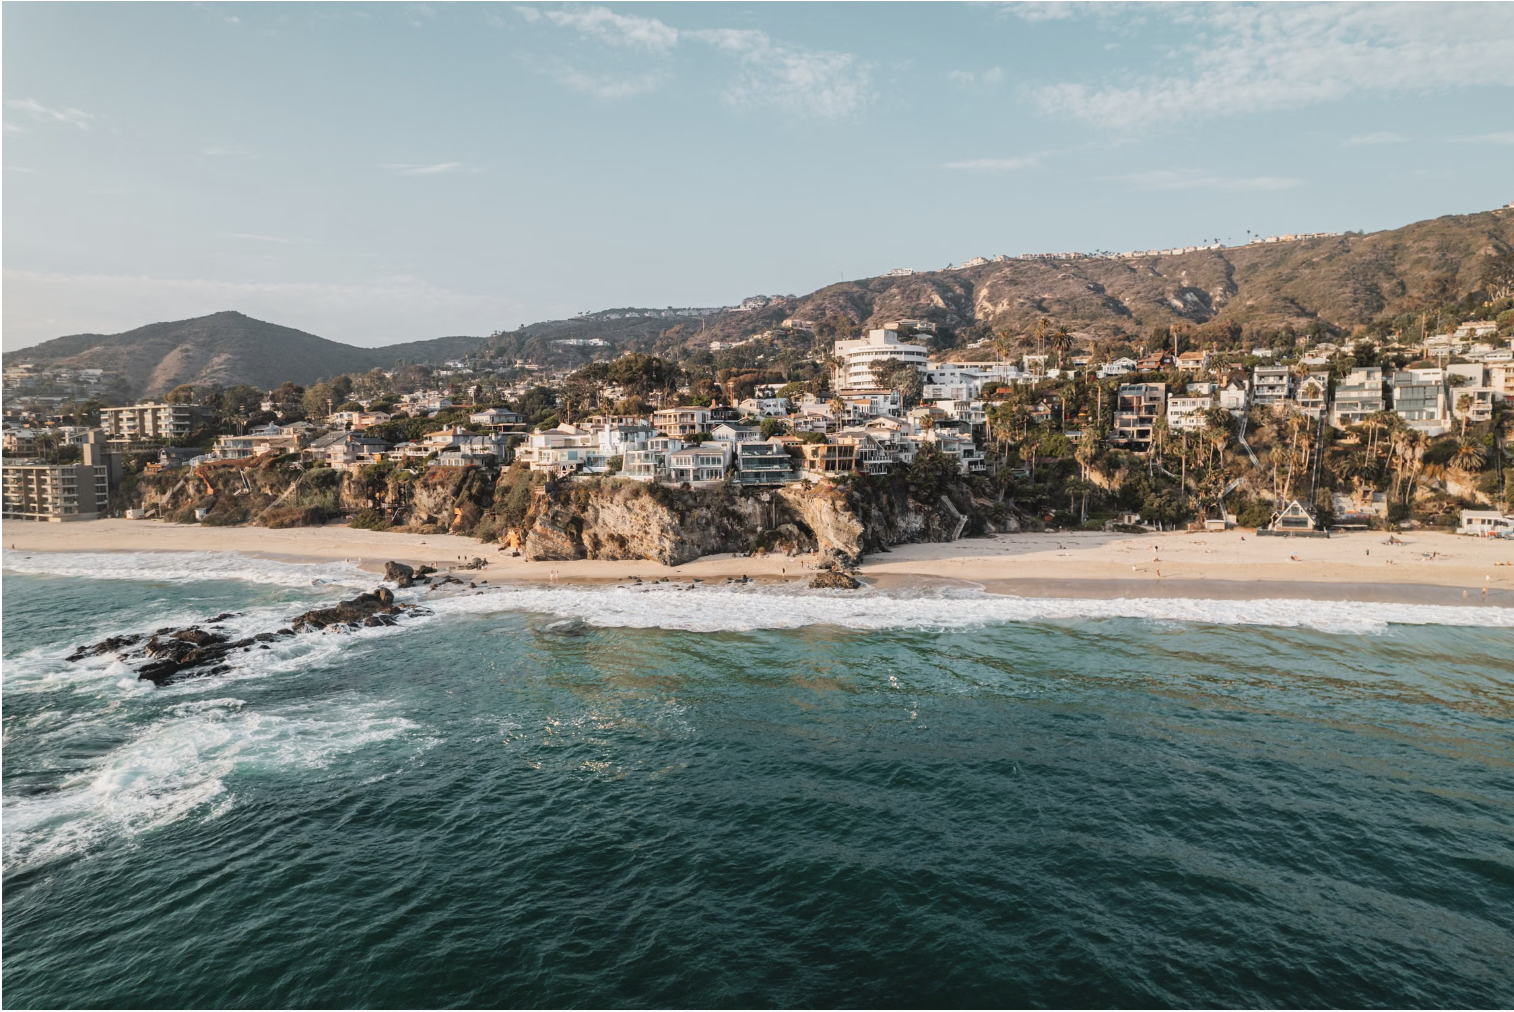
Coastal character, an established artistic identity, distinctive homes, and an intimate connection with the ocean. Look closely at access, parking, hillside terrain and how insurers view a specific property before you commit.
Dana Point
A coastal community with ocean-oriented neighborhoods, harbor access, and a mix of luxury properties and established residential areas.
Dana Point community guide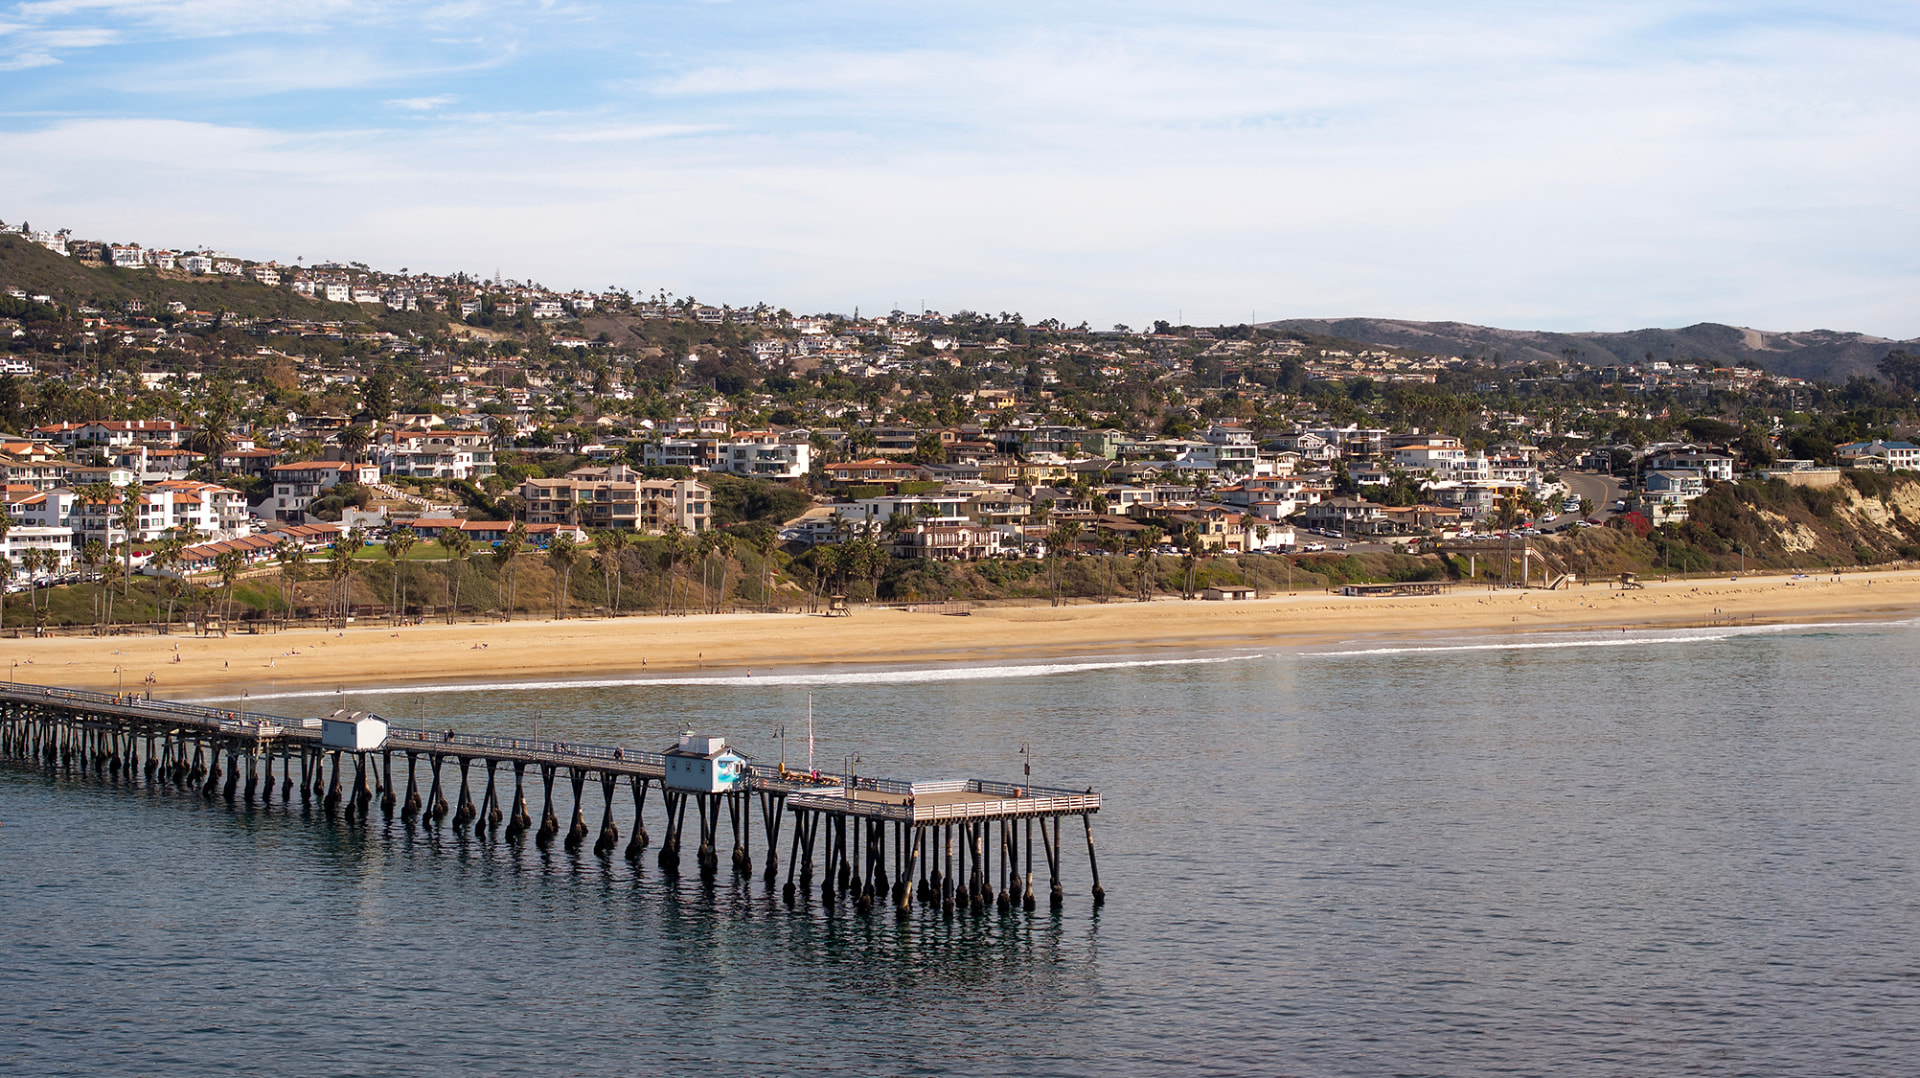
San Clemente
An established beach community with a relaxed coastal atmosphere, distinctive architecture, walkable pockets and a broad range of neighborhood settings.
San Clemente community guide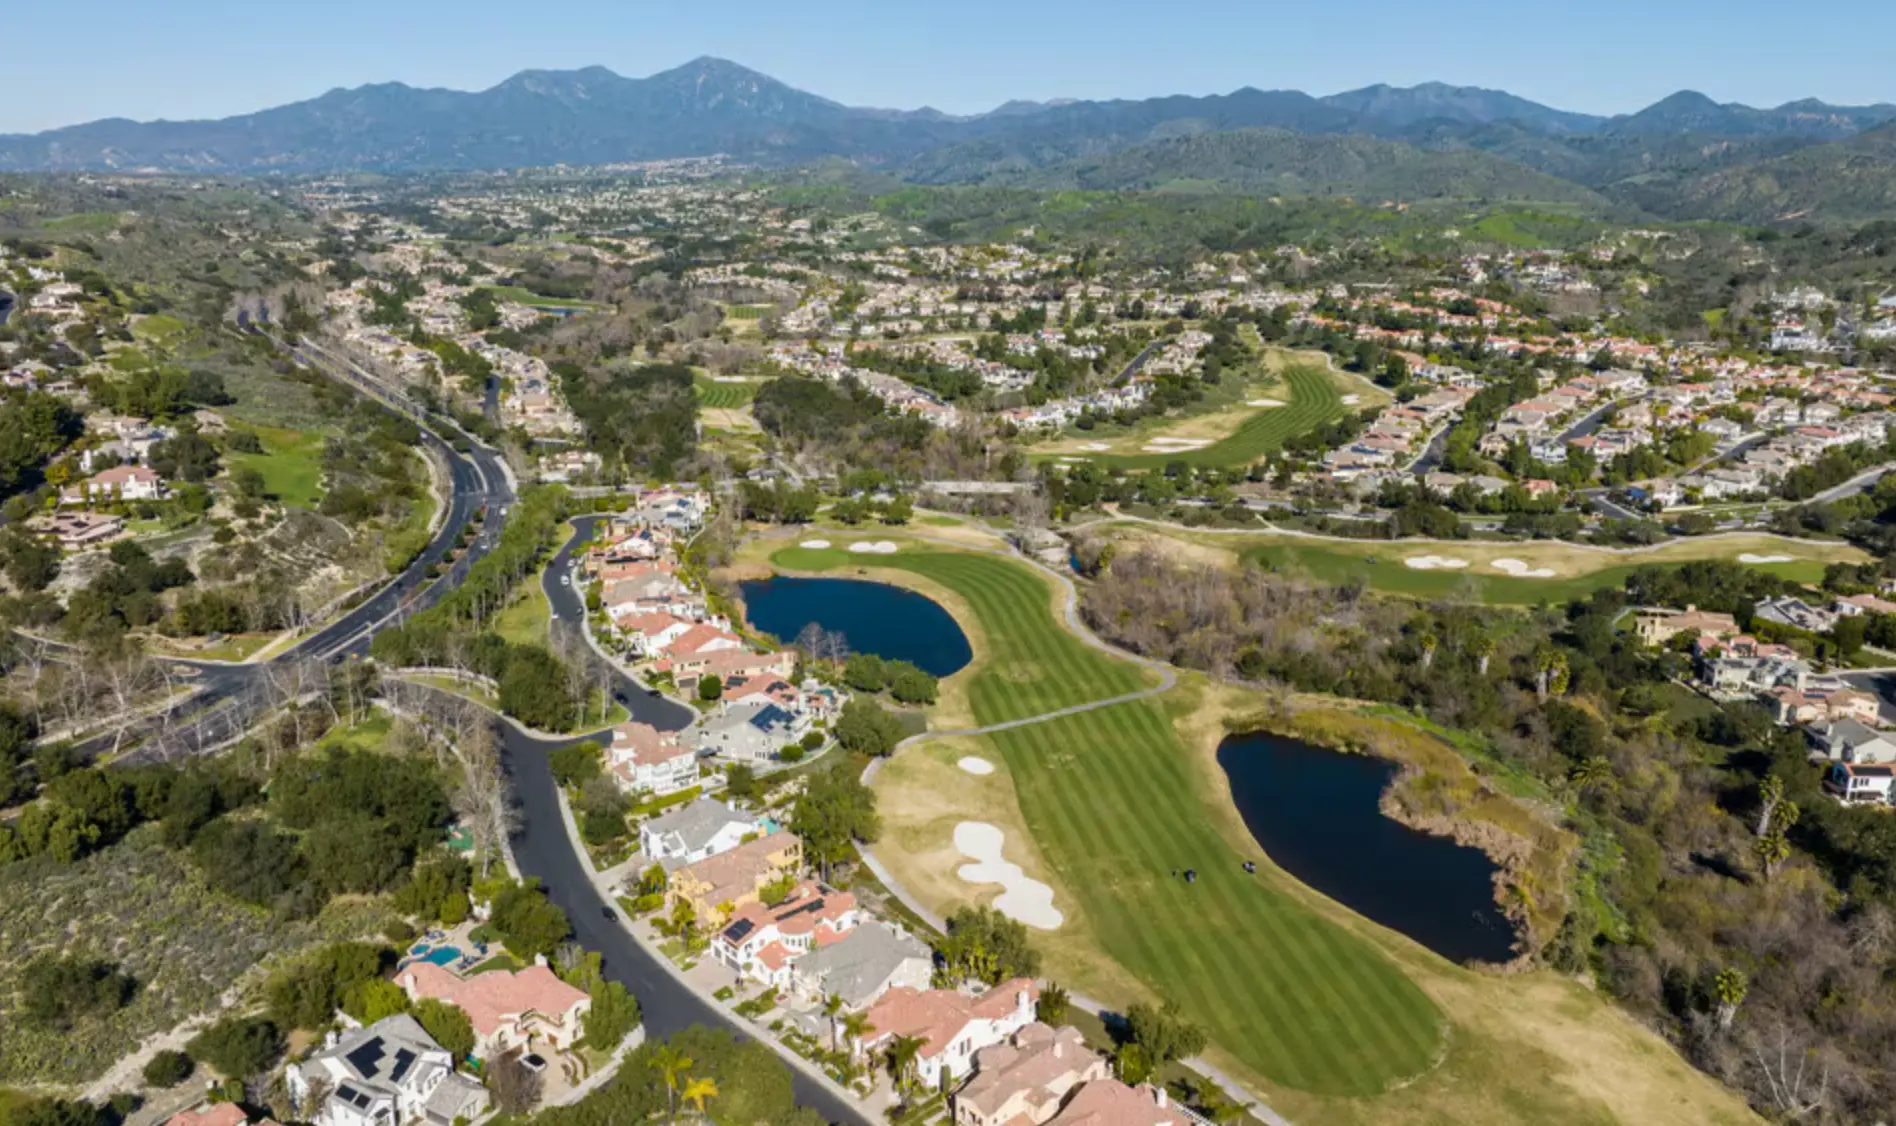
Laguna Niguel
Established residential neighborhoods, parks, coastal proximity and a variety of single-family housing options.
Laguna Niguel community guideLadera Ranch
A master-planned community with parks, trails and neighborhood amenities. Most homes carry HOA dues, and many also carry Mello-Roos taxes, so verify the total for each property.
Ladera Ranch community guide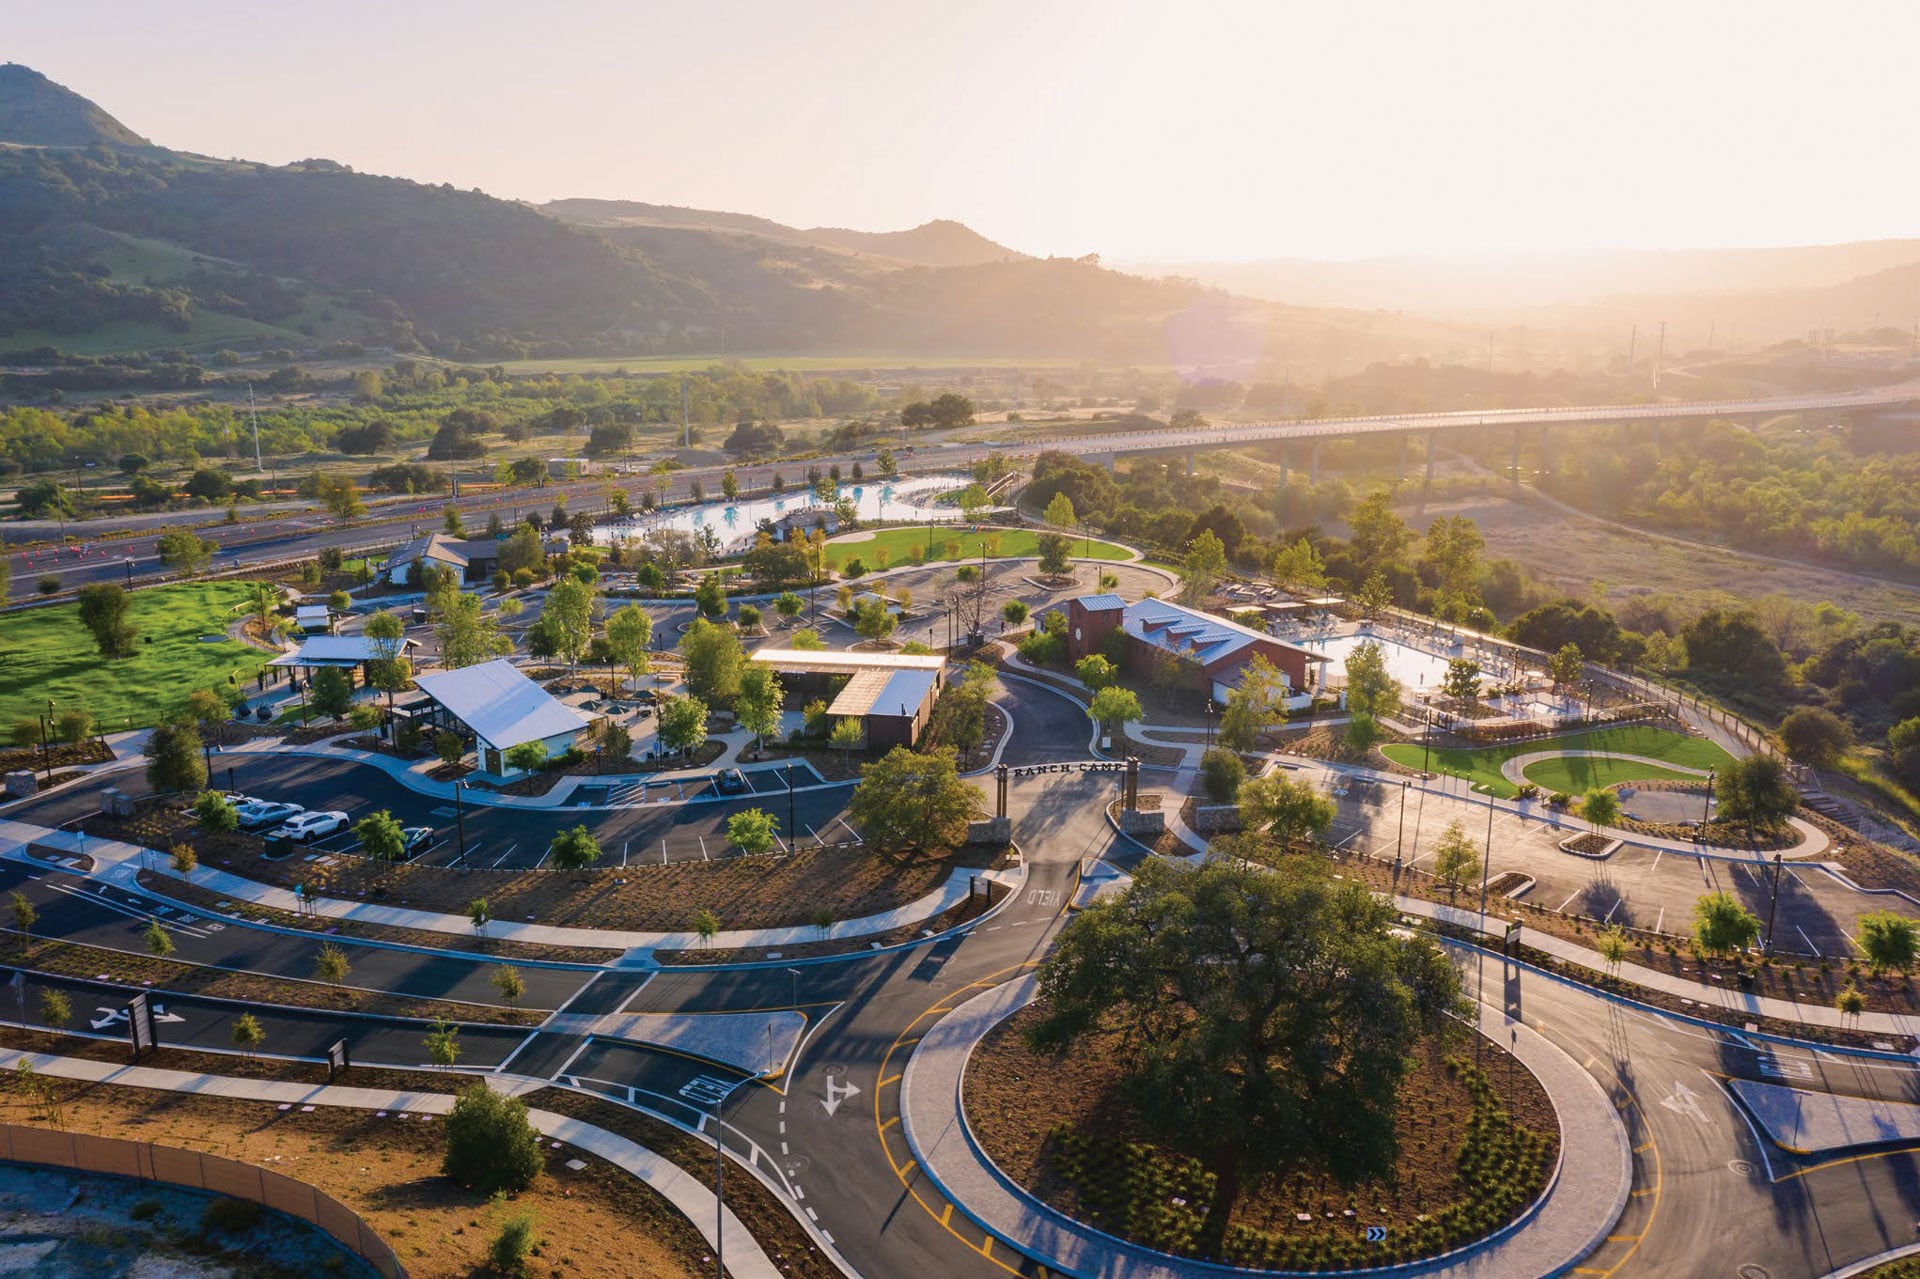
Rancho Mission Viejo
Newer homes, extensive community amenities and modern master-planned neighborhoods with new-construction options. Review HOA dues, special assessments and insurance quotes for each property.
Rancho Mission Viejo community guideIrvine
A major employment center with planned residential villages, parks, amenities and diverse housing options.
Irvine community guideAlso worth a look
Newport Beach
Prioritizing coastal luxury living? Newport Beach is worth exploring too, with harbor and oceanfront neighborhoods just north of South Orange County, though this guide stays focused on South OC.
For schools, use independent sources such as the California Department of Education and individual school district websites.
For buyers
What Should Fire-Displaced Homeowners Consider Before Buying?
Before buying, fire-displaced homeowners should understand how a new purchase fits with the property they still own: the existing mortgage, unresolved insurance claims, potential sale proceeds, lender qualification, and the full cost of owning the new home.
Financial Planning
Map how a purchase may interact with:
- Existing mortgage payments on the original property.
- Insurance claim proceeds and remaining repair or rebuilding costs.
- Outstanding property liens.
- Proceeds from a potential property sale.
- Lender qualification and documented income or assets.
- Down payment and cash reserve requirements.
- Ongoing property taxes, insurance, HOA dues and special assessments.
Don't assume insurance benefits can fund a replacement home, or that insurance-funded rent will cover a mortgage payment. Dwelling coverage, ALE and other benefits each have their own terms. Ask your insurer and your attorney how they apply to your situation.
Property Tax Considerations: Proposition 19
Proposition 19 allows qualifying victims of a wildfire or Governor-declared natural disaster to transfer the property tax base year value of their principal residence to a replacement home anywhere in California, including Orange County.
According to the State Board of Equalization, the replacement home generally must be purchased or newly built within two years of the sale of the original home. If the replacement costs more than the applicable "equal or lesser value" limit, the difference is added to the transferred value. Claims are filed with the assessor in the county where the replacement home is located.
Eligibility is specific and may depend on the original property's use, the severity of damage, whether it is sold in its damaged state, purchase timing and other requirements. Never assume a tax transfer or savings without verifying it with the county assessor and a tax professional.
Homeowners Insurance in Orange County
Moving to Orange County does not eliminate wildfire risk. Many neighborhoods sit near open space, canyons or hillsides, and insurers evaluate each property's wildfire exposure, construction, roof and surroundings when deciding whether to offer coverage and at what price.
Get insurance quotes during your inspection period, before you remove contingencies. Ask about coverage limits, exclusions and deductibles, not just the premium.
If you can't find coverage after shopping the market, the California FAIR Plan is the state's insurer of last resort. According to the California Department of Insurance, it covers a narrower set of perils than a typical homeowners' policy, centered on fire, lightning, internal explosion and smoke, so many owners pair it with a separate difference-in-conditions (DIC) policy.
California Department of Insurance: home insurance and the FAIR Plan
Should You Buy Now or Wait?
Weigh long-term housing stability against current market conditions, your financial readiness, insurance costs in the specific location, and how settled your decisions about the original property really are.
Buying now can end the uncertainty of temporary housing. Waiting can give claims, rebuilding estimates and family plans time to settle. Neither is automatically the smarter choice, and either can be the right one.
Let's map out how a purchase could fit with the property you already own. More on buying in South OC.
Build Your Orange County Buying StrategyFor sellers
Considering Selling Your Palisades Property Instead of Rebuilding?
Selling a fire-affected property can be a practical path for some homeowners, but it is a financial, legal and tax decision as much as a real estate one. Understand the property's current value, your obligations and your remaining claims before deciding.
01
Value of a damaged property or vacant lot
Pricing depends on recent lot and damaged-property sales nearby, what buyers can build, and the state of local rebuilding.
02
Rebuilding costs against sale proceeds
Compare net proceeds from a sale with the full cost and time of rebuilding after insurance.
03
Mortgage and lien considerations
Your lender and any lienholders typically must be paid or agree to terms at closing.
04
Unresolved insurance claims
Ask your insurer and attorney how a sale could affect open claims before you sign a listing agreement or a contract.
05
Tax and Proposition 19
A sale may carry capital gains implications, and the timing of the sale affects Proposition 19 eligibility for a replacement home.
06
Coordinating a sale and a purchase
Selling in Los Angeles and buying in Orange County works best as one plan, with timelines, financing and tax questions sequenced together.
07
Local representation in both markets
Each market has its own buyers, pricing patterns and practices. Having experienced representation on each side helps.
Ronnie's expertise is Orange County real estate and broader California relocation strategy. For the sale of a Palisades property, you may need a Los Angeles agent who knows that market well. Ronnie can help coordinate the Orange County side and the overall plan.
Already Own a Property in Orange County?
Relocation patterns may influence buyer interest in some neighborhoods, but there is no reliable local data showing a measurable surge in demand from displaced fire victims. Price and plan based on what is actually happening in your neighborhood.
That means recent comparable sales, current competing listings, thoughtful presentation and marketing that reaches the buyers most likely to want your home.
You Don't Have to Decide Everything at Once
A decision about where to live is rarely just a real estate decision, especially when the move was never part of the plan.
You may still be waiting on insurance, evaluating rebuilding costs, or deciding whether Orange County is where you want to stay.
The right first step isn't necessarily buying or selling. Sometimes it's simply understanding the options available to you.
A thoughtful plan can help you make your next decision with greater confidence.
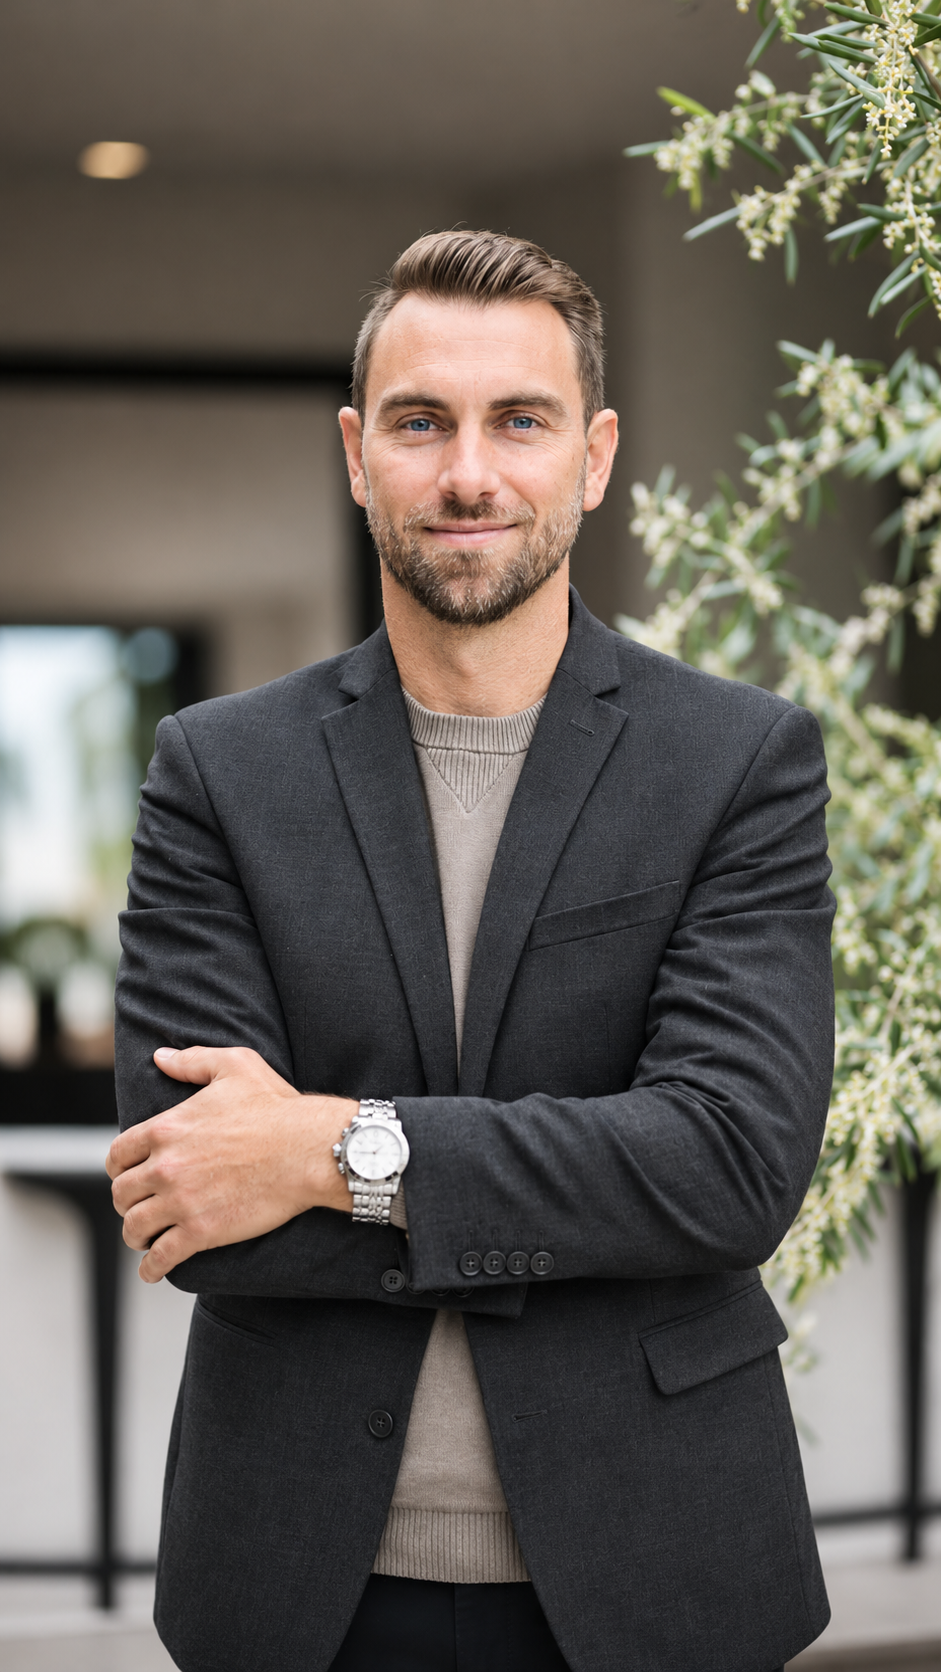
About Ronnie Jenkins
Local Knowledge. California Experience. A Personal Approach.
Ronnie Jenkins is a California REALTOR® affiliated with Compass, with more than 14 years of experience helping clients navigate important real estate decisions.
After building his career in Silicon Valley, Ronnie now lives and works in South Orange County, bringing both extensive California real estate experience and firsthand local knowledge to buyers, sellers and relocating families.
His approach is centered on understanding each client's situation, evaluating their options and building a strategy that supports their goals.
Ronnie Jenkins | REALTOR® | CompassCalifornia DRE #01922959408-784-0378
More about RonnieFrequently Asked Questions About Palisades Fire Housing Assistance and Relocation
When did FEMA rental assistance end for Palisades Fire victims?
FEMA's extended rental-assistance period for eligible renters ended October 9, 2026. Eligible homeowners may continue receiving FEMA financial housing assistance through July 9, 2027, under the extension FEMA approved in June 2026. Eligibility depends on FEMA's criteria, including continued need and a plan for permanent housing. If you're registered with FEMA, call the FEMA Helpline at 800-621-3362 or check DisasterAssistance.gov. FEMA assistance is separate from your homeowners' insurance benefits.
How long does homeowners' insurance pay for temporary housing after a California wildfire?
After a declared state of emergency, California law generally provides at least 24 months of Additional Living Expense (ALE) coverage for a covered loss, according to the California Department of Insurance. Up to 12 more months may be available when reconstruction is delayed by circumstances beyond your control, plus six-month extensions for good cause. Your policy's dollar limit still applies, so check both the time and the dollars remaining.
Can insurance companies stop paying rent before 24 months?
Yes, if the policy's ALE dollar limit is used up. The California Department of Insurance notes that some policies have a dollar limit that can be exhausted before the time limits end. ALE can also end when the home becomes livable again, and renters' policies often cover a shorter period. Ask your insurer for your remaining balance in writing, and contact the Department of Insurance at 1-800-927-4357 if you have a dispute.
Can displaced homeowners request an extension of their Additional Living Expense coverage?
Yes. Under California law, policyholders may be entitled to an additional 12 months of ALE when reconstruction is delayed by circumstances beyond their control, such as permitting or contractor availability, and further six-month extensions for good cause. Extensions do not increase a policy's dollar limit. Request extensions in writing, document the reasons for delay, and keep copies of your communications with your insurer.
Can I buy a new house while my Palisades home is being rebuilt?
Yes, if you can qualify for financing and carry the costs. Lenders will look at your existing mortgage and other obligations alongside the new loan. Insurance benefits are tied to your policy terms and may not cover a new mortgage, and buying a second home can change how some benefits apply. Talk with your insurer, lender and a financial advisor before making an offer.
Can I sell my fire-damaged property and buy in Orange County?
Yes. Some homeowners sell a damaged home or lot and buy elsewhere. It works best as one coordinated plan covering the sale price, mortgage payoff, open insurance claims, tax implications and the timing of the Orange County purchase. You will likely want a Los Angeles agent for the Palisades sale and an Orange County agent for the purchase, along with independent legal and tax advice.
Does Proposition 19 help wildfire victims purchase replacement homes?
It can. Proposition 19 allows qualifying wildfire victims to transfer the property tax base year value of their principal residence to a replacement home anywhere in California, generally purchased within two years of the original home's sale. If the replacement costs more than the allowed value, the difference is added. Eligibility has specific requirements, so confirm with the State Board of Equalization, the Orange County Assessor and a tax professional.
Should I continue renting in Orange County or consider buying?
It depends on how certain your plans are. Buying can provide stability if you expect to stay several years and can qualify comfortably. Renting longer may be wiser if insurance, rebuilding or a sale is still unresolved, or if you're still deciding whether Orange County is home. Compare the full monthly cost of each option, including the property you still own.
What are the best Orange County communities for someone relocating from Pacific Palisades?
There is no single best community. It depends on what you want daily life to look like. Families drawn to the coast often explore Laguna Beach, Dana Point and San Clemente. Those who want parks, trails and newer homes often look at Ladera Ranch and Rancho Mission Viejo, while Irvine offers employment access and planned villages. Compare commutes, ownership costs, insurance and housing types.
How can I find an Orange County REALTOR® who understands complex relocation decisions?
Look for someone who asks about your whole situation, including the property you still own, your insurance and your timeline, before talking about homes. They should know the specific communities you're considering, explain HOA and Mello-Roos costs clearly, and be candid about what's outside their expertise. Ask how they would coordinate with your lender, tax advisor and any Los Angeles agent.
Sources and Further Reading
- Office of Governor Gavin Newsom, Governor Newsom welcomes FEMA extension to help Los Angeles fire survivors continue recovery. Published .FEMA IHP financial housing assistance extended for eligible homeowners through July 9, 2027, and for eligible renters through October 9, 2026.
- California Governor's Office of Emergency Services (Cal OES), Continued Temporary Housing Assistance Still Available for Los Angeles County Wildfire Survivors. Published .Eligibility for FEMA Rental Assistance and Continued Temporary Housing Assistance, and how to apply.
- California Department of Insurance, Insurance coverage for additional living expenses if the home is not habitable due to a wildfire2025 consumer alert summarizing California Insurance Code section 2060(b)(1).
- Department of Angels, “It's Awful to Lose Your Roots”: Los Angeles Fire Recovery at 20 Months. Published .Survey of more than 2,000 fire-impacted residents across Altadena, Pacific Palisades, Malibu and Pasadena, August 25 to September 8, 2026.
- California State Board of Equalization, Proposition 19: The Home Protection for Seniors, Severely Disabled, Families, and Victims of Wildfire or Natural Disasters ActBase year value transfer rules for disaster victims, including timing and value limits.
- California Department of Insurance, Home/Residential Insurance: What If I Can't Find Insurance?Shopping for residential insurance, the California FAIR Plan as insurer of last resort, and what a FAIR Plan policy covers.
Dates, deadlines and survey figures are reported facts from the sources above. Guidance on buying, selling and choosing a community is Ronnie's professional real estate perspective. This guide is general information, not legal, tax, insurance or financial advice. Program rules, deadlines and policy terms change and vary by household. Ronnie Jenkins is a REALTOR®, not an attorney, tax advisor, public adjuster or insurance professional. Consult the appropriate professionals and agencies about your specific situation. Last reviewed .